
The 50/30/20 Rule Explained for Mid-Career Earners
Learn how the 50/30/20 budgeting framework works and how to adapt it when retirement savings become your top financial priority.
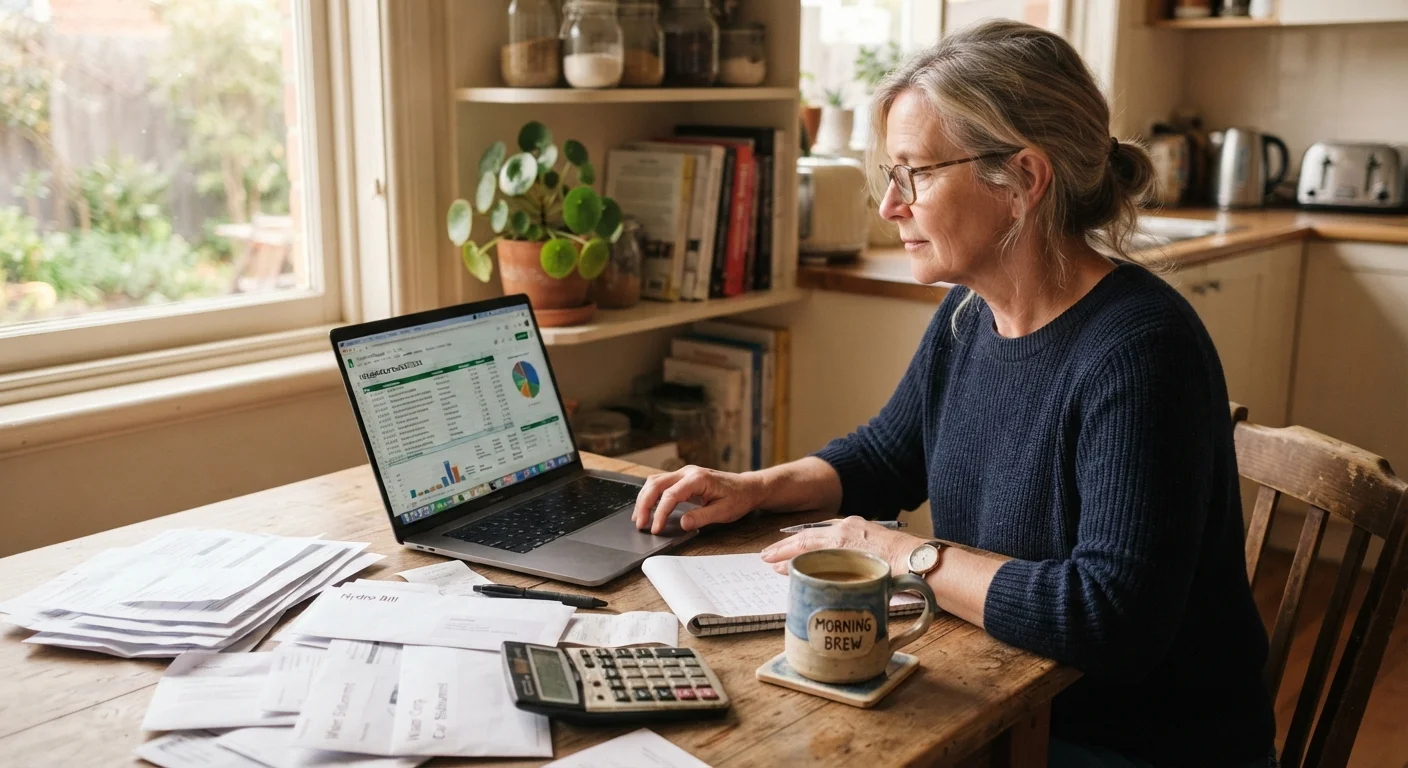
Photo: investorspaces.com editorial
—— In This Article
Key Takeaways
- The 50/30/20 rule splits after-tax income into needs, wants, and savings in a simple three-category framework.
- Mid-career earners who are behind on retirement savings may need to push the savings slice to 25% or 30%.
- Reducing the 'wants' category by even 5 percentage points can meaningfully increase annual retirement contributions.
- IRS contribution limits for 401(k) and IRA accounts set the ceiling for tax-advantaged retirement saving each year.
- Automating transfers to retirement accounts before spending on wants removes the temptation to skip contributions.
How the three categories actually work
After-tax (take-home) pay is the starting number. From there, the rule allocates 50% to needs, 30% to wants, and 20% to savings and debt repayment. Those percentages are meant to be approximate guides, not hard rules.
Needs include rent or mortgage payments, utilities, groceries, health insurance premiums, minimum loan payments, and basic transportation costs. Wants cover anything that improves quality of life but is not strictly required: restaurant meals, vacations, hobbies, and subscription services. The savings category is where retirement contributions, emergency fund deposits, and extra debt payments live.
The framework is designed to be low-maintenance. You do not need a spreadsheet with 40 rows. The tradeoff is less precision, which matters more as your financial situation gets complicated by a mortgage, dependents, and a growing retirement gap.
Why the standard split does not fit mid-career reality
The 20% savings target was reasonable guidance when it was written, but it assumes a saver who started contributing consistently in their 20s. Many mid-career earners did not. Bureau of Labor Statistics Consumer Expenditure Survey data consistently shows that households in the 45-to-54 age range spend a large share of income on housing and transportation, leaving the savings slice compressed.
If your retirement account balances are below where they need to be, a flat 20% savings rate may not close the gap before retirement. The math is straightforward: a 50-year-old with less than $250,000 saved who wants to retire at 65 with a comfortable income will need to save at a higher rate than someone who started at 22 and has been consistent.
This does not mean the framework is useless. It means the savings slice needs to expand, and the wants slice is where that room comes from. For mid-career earners, a 50/25/25 or even a 50/20/30 split is worth modeling. Those extra percentage points directed at retirement contributions can add up significantly over 15 years.
Automate before the money lands
The most reliable way to sustain a higher savings rate is to never see the money in your checking account. Increase your 401(k) payroll deferral percentage or set up an automatic transfer to an IRA on payday. Waiting until the end of the month to save what is left over consistently produces smaller contributions than automation does.
If you are 50 or older, the IRS allows catch-up contributions above the standard annual limits for 401(k) and IRA accounts. See how to build a budget that uses those higher limits before those years pass.
Practical steps to shift the split
Start by calculating your actual after-tax monthly income, then map your current spending to the three categories. Most people find that wants are larger than expected and needs contain some expenses that could be reclassified or reduced.
Common wants that mid-career earners can reduce without meaningful lifestyle disruption include multiple streaming subscriptions, frequent restaurant meals, and vehicle upgrades that go beyond basic transportation needs. The Bureau of Labor Statistics data shows food away from home and entertainment are among the largest discretionary line items for this age group.
Once you identify the gap, automate the difference. Set up a payroll deduction or automatic transfer to your retirement account that moves the additional savings before you see the money in your checking account. Behavioral finance research, including work published by academic economists such as Shlomo Benartzi and Richard Thaler, consistently finds that automation is more effective at sustaining savings behavior than relying on monthly willpower decisions.
Run a monthly budget audit to track whether the new split is holding. Spending categories tend to drift, especially in months with irregular expenses like home repairs or medical bills.
Where retirement contributions fit in the savings slice
The 20% (or higher) savings allocation has to cover several competing goals: retirement contributions, emergency fund maintenance, and debt reduction beyond minimum payments. Mid-career earners often find these goals pulling in different directions.
A practical ordering is to first contribute enough to a workplace retirement plan to capture any employer match, because that match is part of your compensation and leaving it on the table is a direct reduction in pay. After that, build or maintain a liquid emergency fund. Then direct remaining savings capacity toward maxing tax-advantaged accounts.
For context, the IRS sets annual contribution limits for 401(k) plans and IRAs, and those limits change periodically. Checking current IRS guidance or consulting a licensed financial adviser will give you the exact figures applicable in your filing year. The catch-up contribution rules for savers over 50 allow higher limits that can accelerate progress significantly in the final working years.
The 50/30/20 rule does not tell you how to split the savings slice internally, so you need to make that decision deliberately. A written plan, even a simple one, makes it easier to stick to the allocation when competing expenses arise. For a broader view of how these priorities fit your decade of life, the decade-by-decade personal finance framework offers useful context.
This article is for informational purposes only and does not constitute personalized financial, tax, or investment advice. Consult a qualified financial adviser for guidance specific to your situation.
Frequently Asked Questions
Budgeting & Saving Editorial Team
Budgeting & Saving Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile