
Building Your First Investment Portfolio Step by Step
A practical walkthrough for middle-aged investors ready to build a structured, goal-focused portfolio from the ground up.
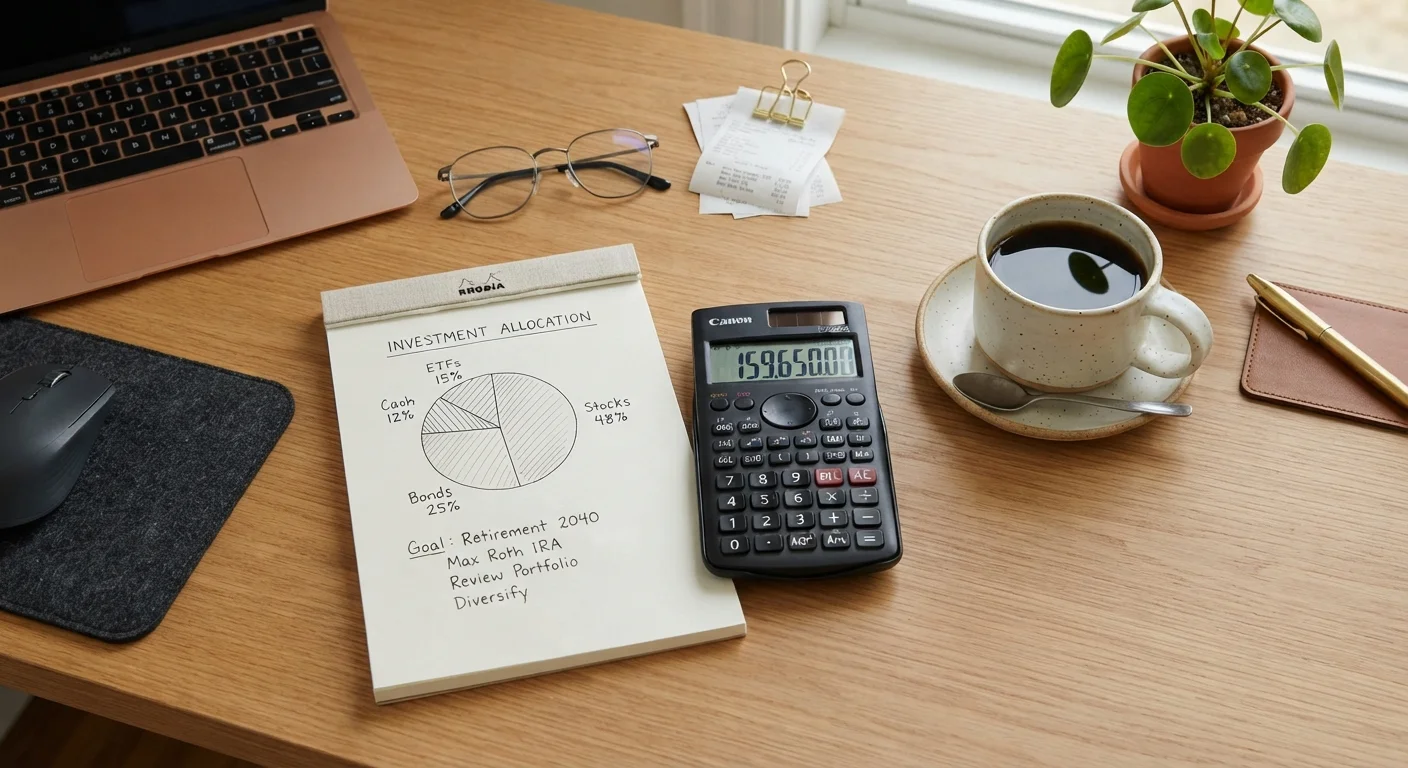
Photo: investorspaces.com editorial
—— In This Article
Key Takeaways
- Clarifying your retirement timeline and income needs is the essential first step before selecting any investments.
- Asset allocation, dividing money across stocks, bonds, and cash, shapes your portfolio's risk and growth potential more than individual fund picks.
- Low-cost, broadly diversified funds such as index funds can give exposure to hundreds of securities in a single purchase.
- Rebalancing once or twice a year keeps your target allocation intact as market prices shift.
- All investments carry risk, and past performance does not guarantee future results.
Why structure matters before you pick a single investment
Many investors start by picking individual stocks or funds and work backward toward a strategy. That approach tends to produce a scattered mix of holdings without a coherent risk profile. A structured process, starting with goals and ending with specific securities, gives each decision a reason.
This walkthrough covers the practical sequence: define what you need, determine how much risk you can carry, choose an asset mix, select vehicles to fill each piece of that mix, and then maintain the result over time. For a plain-language reference on terms such as expense ratio, rebalancing, and diversification, see the investor glossary before working through the steps below.
Nothing here is personalised investment advice. Consult a licensed financial adviser for guidance specific to your situation.
What you will need before starting
Gather the following before working through the steps.
What you will need
Step-by-step: building your portfolio
Follow these steps in order. Skipping ahead, particularly past goal-setting and risk assessment, makes later decisions harder to justify and easier to second-guess during a market downturn.
Define your retirement goal in concrete numbers
Write down two figures: the age you plan to stop working and the annual income you expect to need in retirement. A common starting point is 70 to 80 percent of your current pre-tax income, though your actual number depends on your expected expenses, housing situation, and health costs.
The gap between what Social Security and any pension will provide and your total income target is the amount your portfolio needs to generate. That gap drives every decision that follows.
Assess your risk tolerance and time horizon
Risk tolerance is how much short-term loss you can accept without abandoning your plan. Time horizon is how many years until you need to draw on the money. These two factors together determine how aggressively or conservatively you should invest.
A 52-year-old with a 15-year horizon can generally hold more in equities (stocks) than a 62-year-old who plans to retire in three years. Equities carry higher long-run growth potential but can lose 30 percent or more in a downturn. Bonds tend to be more stable in price but generate lower long-term returns. Neither is inherently right; the proportion matters.
For a thorough grounding in how these proportions interact, see the asset allocation fundamentals guide.
Set a target asset allocation
Asset allocation is the percentage split between broad investment categories, primarily stocks, bonds, and cash or cash equivalents. A widely used rule of thumb suggests subtracting your age from 110 to arrive at a stock percentage (for example, 110 minus 52 equals 58 percent equities), but this is a starting point, not a formula. Your specific income gap, risk tolerance, and other assets may call for a different mix.
Within equities, consider splitting between domestic and international stocks for geographic diversification. Within fixed income, consider varying maturities (short-term versus intermediate-term bonds) to manage interest-rate sensitivity.
Choose investment vehicles to fill each allocation slice
Once you have a target allocation, select broadly diversified, low-cost funds to fill each category. Index funds and exchange-traded funds (ETFs) track a market index, such as the S&P 500 or the Bloomberg U.S. Aggregate Bond Index, and typically carry lower expense ratios than actively managed funds. The expense ratio is the annual cost expressed as a percentage of assets; even a difference of 0.5 percent compounds significantly over 15 years.
A simple three-fund approach, one domestic stock index fund, one international stock index fund, and one bond index fund, covers most of the allocation combinations a long-term investor needs. More complex structures are possible but are not necessary to build a well-diversified portfolio.
Open or designate accounts and make initial contributions
Match each investment to the right account type. Tax-advantaged accounts (traditional 401(k), traditional IRA, Roth IRA) shelter growth from current or future taxes. Bonds, which generate taxable interest, are often more efficient inside a tax-deferred account. Broadly diversified stock index funds can be held in either taxable or tax-advantaged accounts.
Contribute up to any employer match in your 401(k) first; an employer match is an immediate return on that contribution. Then consider maxing an IRA before adding further to a taxable brokerage account. Contribution limits and eligibility rules change, so verify current figures with the IRS or a tax professional.
For a broader framework on how these decisions fit into your financial life in the years before retirement, see the decade-by-decade personal finance framework.
Schedule regular rebalancing reviews
Set a calendar reminder to review your allocation once or twice a year, or after any market move that shifts a category more than five percentage points from its target. Rebalancing means selling a portion of what has grown above target weight and buying more of what has fallen below it. This is a disciplined way to sell relatively high and buy relatively low over time.
Avoid rebalancing more frequently than quarterly; transaction costs and tax events in taxable accounts can erode the benefit. In tax-advantaged accounts, rebalancing has no immediate tax consequence, making it simpler to execute.
This article is for informational purposes only and does not constitute personalised investment, tax, or legal advice. Consult a qualified financial adviser, accountant, or attorney for guidance tailored to your circumstances.
Keeping the portfolio working over time
Building a portfolio is not a one-time event. Markets move, and after a strong year in equities your stock allocation may have drifted well above your target, taking on more risk than you planned for. An annual or semi-annual review lets you sell a portion of what has grown and add to what has lagged, restoring the original mix.
Life changes also call for review. A job change, inheritance, or shift in expected retirement date can alter how much risk you can afford to carry. If you are mapping these decisions across your 50s and 60s, the retirement readiness roadmap outlines what to focus on at each stage. And when you are close to stopping work, the pre-retirement audit checklist offers a structured review of estate documents, beneficiary designations, and tax position.
Investing Basics Editorial Team
Investing Basics Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile