
Emergency Funds vs. Retirement Contributions: Finding the Right Balance
Should you build a cash cushion or prioritise retirement investing? Understand the trade-offs and how to approach both goals at the same time.
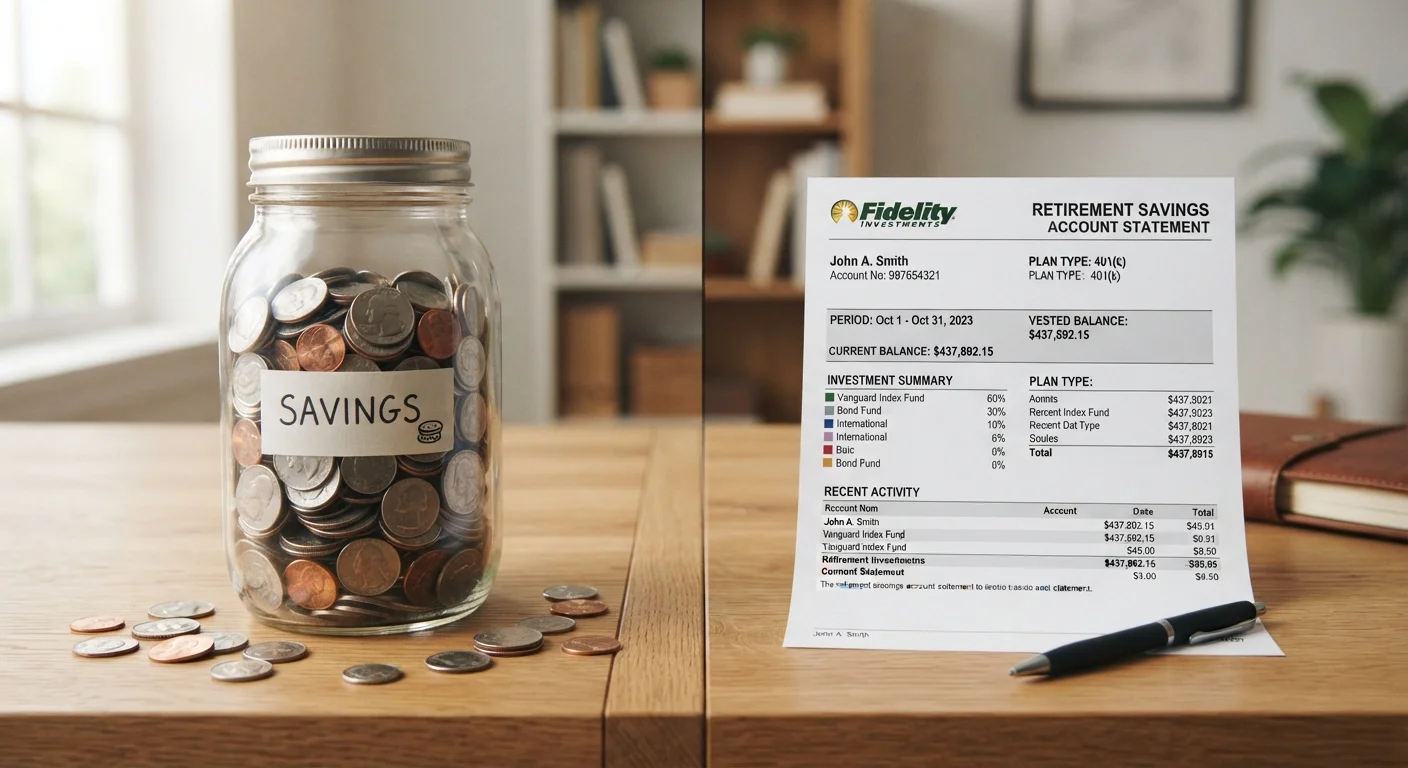
Photo: investorspaces.com editorial
—— In This Article
Key Takeaways
- A cash emergency fund prevents forced withdrawals from retirement accounts, which trigger taxes and penalties.
- Employer 401(k) matches are an immediate guaranteed return that most financial planners consider worth capturing first.
- Three to six months of living expenses is the standard emergency fund target, though individual circumstances vary.
- Both goals can run in parallel once a minimum cash buffer is in place.
- Withdrawing retirement funds early can cost 10% in penalties plus ordinary income tax on the amount taken.
Why this trade-off matters more at midlife
For middle-aged workers, the cost of getting this wrong is high in both directions. Neglect the emergency fund and one medical bill or job loss forces an early retirement account withdrawal, which the IRS taxes as ordinary income and typically hits with a 10% early withdrawal penalty on top. Neglect retirement contributions too long and the lost compounding is simply gone: time cannot be bought back.
The decision is not really either/or. It is a question of sequencing and proportion. Understanding what each goal does and what it costs to skip it helps clarify the order. For broader context on how daily financial choices connect to retirement readiness, the Budgeting and Saving hub covers the full picture.
What each vehicle actually does
An emergency fund is liquid cash, typically in a high-yield savings or money market account, set aside for unplanned expenses. It does not grow significantly. Its job is availability. The standard guidance from the Consumer Financial Protection Bureau and most financial planning frameworks targets three to six months of essential living expenses, though people with variable income or a single earner household may want more.
Retirement contributions go into tax-advantaged accounts such as a 401(k), 403(b), or IRA. The money is not meant to be touched before age 59.5. In exchange for that constraint, contributions to traditional accounts reduce taxable income now, and the balance compounds without annual tax drag. Roth accounts work differently: contributions are post-tax, but qualified withdrawals are tax-free. For a side-by-side look at those two structures, see the Traditional IRA vs. Roth IRA comparison.
| Criterion | Emergency fund | Retirement contributions |
|---|---|---|
| Primary purpose | Liquidity for unexpected costs | Long-term wealth accumulation |
| Account type | Savings or money market account | 401(k), IRA, 403(b), or similar |
| Tax benefit | None (interest is taxable) | Tax deferral or tax-free growth |
| Access to funds | Immediate, no penalty | Restricted before age 59.5 |
| Early withdrawal cost | None | 10% penalty plus income tax |
| Employer contribution | None | Match possible (varies by plan) |
| Target amount | 3 to 6 months of expenses | Set by contribution limits and goals |
The employer match: a hard number to ignore
If your employer matches 401(k) contributions, that match is the closest thing to a guaranteed return in personal finance. A common structure matches 50 cents per dollar up to 6% of salary. On a $70,000 salary, contributing 6% generates $2,100 in matching funds annually. Forgoing that to build an emergency fund faster means leaving real compensation on the table.
Most financial planners treat capturing the full employer match as the first retirement savings priority, even before a complete emergency fund. The logic is straightforward: the match return (50% to 100% on those dollars) typically exceeds the effective cost of having a thinner cash buffer, especially if you have access to a low-interest line of credit as a backup. For workers over 50 looking to close savings gaps, catch-up contribution rules raise the annual limits further.
Running both goals at the same time
Once the employer match is captured, the practical approach for most households is to fund both goals simultaneously rather than completing one before starting the other. A common split: contribute enough to get the full match, then divide remaining discretionary income between the cash reserve and additional retirement contributions until the emergency fund reaches its target. After that, redirect the cash portion entirely to retirement saving.
Automation makes this easier to execute consistently. Setting up automatic transfers for both a savings account and a retirement account removes the monthly decision and reduces the chance that spending absorbs the money first.
Your savings rate matters across both goals. Every dollar diverted to cash savings still builds your household balance sheet, even if it does not compound in a tax-advantaged account. The goal is to make sure neither bucket is chronically empty.
This article is for informational purposes only and does not constitute personalised financial, tax, or investment advice. Consult a qualified financial adviser or tax professional regarding your specific circumstances.
Personal Finance Editorial Team
Personal Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile