
Social Security and Taxes: When Your Benefits Become Taxable Income
Up to 85 percent of Social Security benefits can be subject to federal income tax depending on your combined income. Learn how the threshold is calculated.
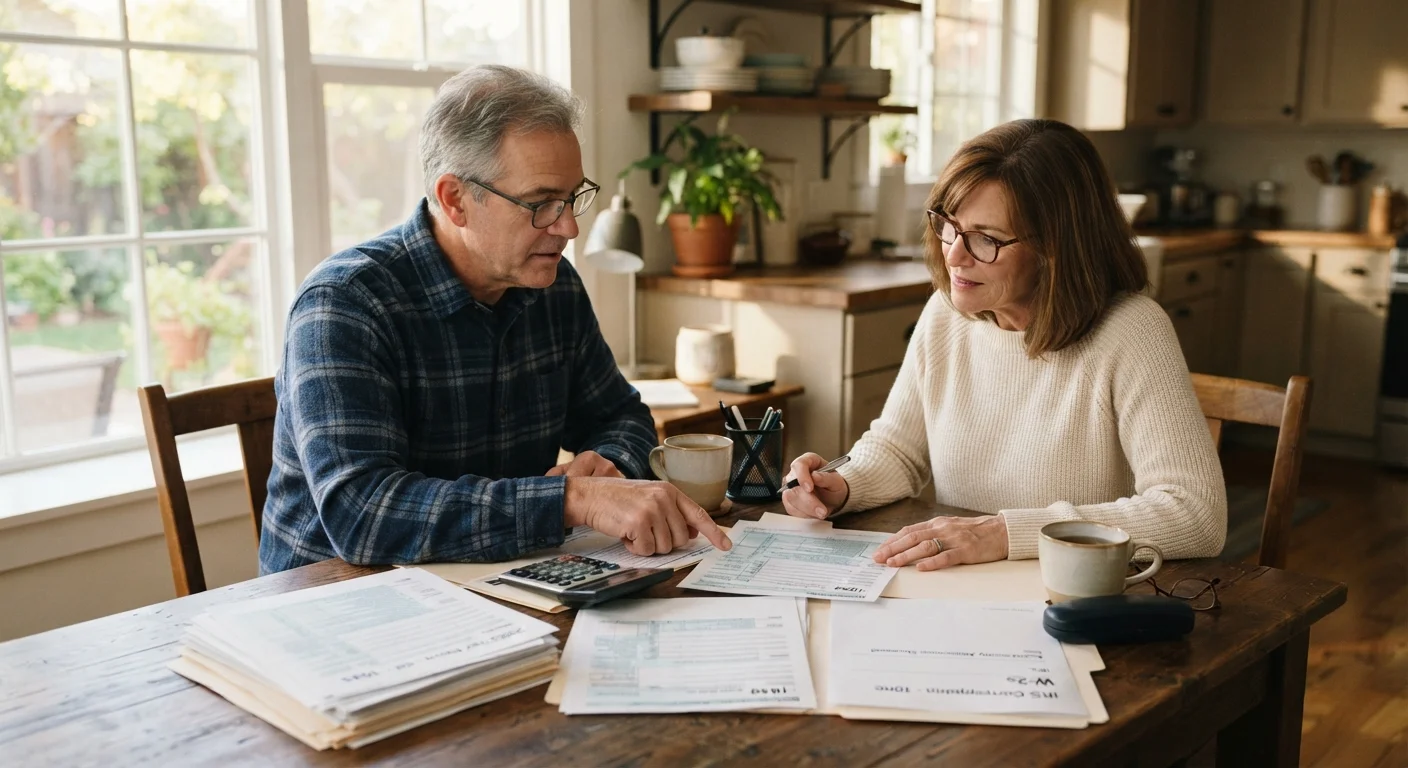
Photo: investorspaces.com editorial
—— In This Article
Key Takeaways
- Up to 85% of Social Security benefits can be subject to federal income tax, but no more than 85% is ever taxable.
- The IRS uses 'combined income' (adjusted gross income plus nontaxable interest plus half your Social Security benefit) to determine taxability.
- Single filers with combined income above $25,000 and married joint filers above $32,000 face some benefit taxation.
- The thresholds have not been adjusted for inflation since they were enacted, so more retirees cross them over time.
- Claiming age and other income sources both affect how much of your benefit is taxable each year.
- A qualified tax professional can help you plan withdrawals and income timing to manage your tax exposure.
How the IRS measures your Social Security income
The Social Security Administration pays benefits, but the IRS decides how much of those benefits are taxable. The central tool is a figure the IRS calls combined income, defined as:
- Your adjusted gross income (AGI), which includes wages, pension income, traditional IRA or 401(k) withdrawals, and most other taxable income
- Plus any tax-exempt interest income, such as interest from municipal bonds
- Plus 50% of your annual Social Security benefit
That total is compared against two thresholds that differ by filing status. For single filers, if combined income falls between $25,000 and $34,000, up to 50% of benefits may be taxable. Above $34,000, up to 85% may be taxable. For married couples filing jointly, the 50% range runs from $32,000 to $44,000, and the 85% ceiling applies above $44,000.
The phrase 'up to 85%' means 85% is the maximum portion of your benefit included in taxable income. The federal government does not tax the full benefit under any circumstance.
Married filing separately: a different outcome
Taxpayers who are married but file separately face a much stricter rule. The IRS treats a $0 threshold for this filing status, meaning virtually all of their Social Security benefit may be taxable regardless of income level. Most financial advisers recommend that married retirees avoid this filing status unless there is a compelling legal or financial reason to use it.
Why more retirees are reaching the taxable threshold
Congress set the current thresholds in 1983 (for the 50% tier) and 1993 (for the 85% tier). Neither amount has been adjusted for inflation. A retiree with modest pension income and average Social Security benefits now often surpasses $25,000 or $32,000 in combined income without earning what most people would consider a high income. Required minimum distributions from traditional IRAs and 401(k) plans count toward AGI and push many retirees across the threshold even when their cash needs are modest.
This matters for withdrawal planning. A large IRA distribution in a single year can temporarily spike combined income and increase the taxable share of Social Security for that year. Spreading withdrawals over multiple years, or converting traditional IRA balances to Roth accounts in lower-income years before claiming Social Security, are strategies some retirees consider. Any such plan warrants review by a qualified tax adviser because individual circumstances vary considerably.
How claiming age and spousal benefits intersect with taxation
The age you claim Social Security affects your monthly benefit amount, which in turn affects the Social Security portion of your combined income calculation. A higher monthly benefit means the 50% inclusion figure is larger, which can push combined income above a threshold. For some retirees, delaying to age 70 produces a larger check but also a larger taxable component. Whether that trade-off is favorable depends on your other income sources and marginal tax rate.
Spousal benefits follow the same federal tax rules. If you receive a spousal benefit (up to 50% of your spouse's primary insurance amount), that amount counts in your own combined income calculation just as a worker benefit would. Married couples should consider the combined income of the household, since both spouses' benefits and income sources appear on a joint return. For more on how spousal benefits are calculated, see how spousal Social Security benefits are calculated and who qualifies.
Couples sometimes find that coordinating claim dates, for example one spouse claiming early while the other delays, alters their combined income profile in each year and can shift which tax tier applies. See what claiming age numbers actually mean for retirement income for a fuller treatment of timing trade-offs.
Practical steps for managing benefit taxation
A few concrete factors are worth tracking each year:
- Calculate your projected combined income before the year ends, using your expected AGI, any tax-exempt interest, and 50% of your estimated annual benefit.
- Check whether a large IRA withdrawal, Roth conversion, or sale of a taxable investment will push you into a higher combined income tier.
- If you have not yet claimed Social Security, consider how your current income sources will interact with your benefit amount under different claiming scenarios.
- Review whether voluntary withholding from your Social Security benefit (using IRS Form W-4V) makes sense so you avoid a large tax bill in April.
If you are still working while receiving benefits before full retirement age, earned wages raise your AGI and therefore your combined income. Working while collecting Social Security before full retirement age involves both an earnings limit on benefits and a tax consideration on any benefit you do receive.
This article is for general informational purposes only and does not constitute tax, legal, or financial advice. Tax rules and thresholds are subject to legislative change. Consult a qualified tax professional or financial adviser regarding your specific circumstances.
Frequently Asked Questions
Social Security Editorial Team
Social Security Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile