
Closing the Retirement Gap: Redirecting Everyday Spending
Discover practical ways to identify spending leaks and redirect that money toward retirement contributions without upending your lifestyle.
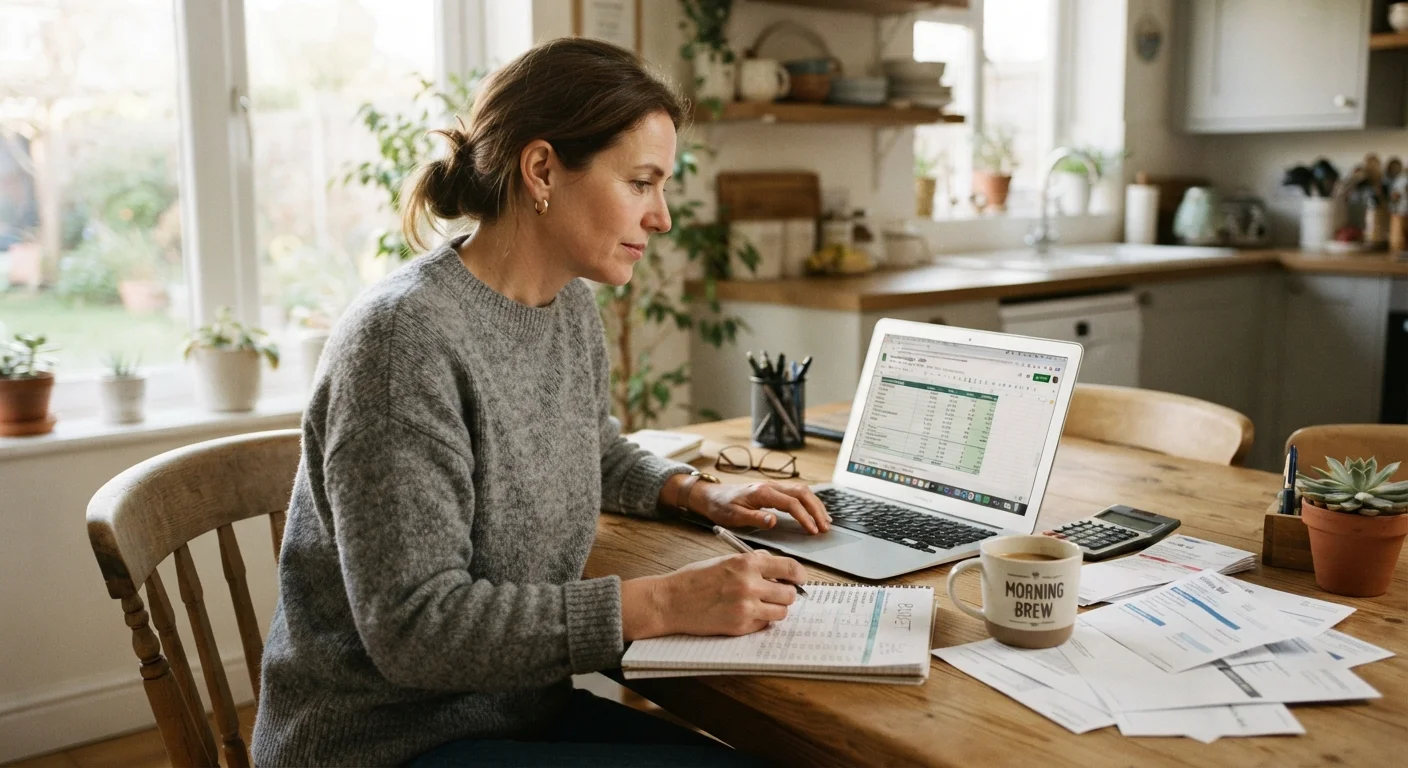
Photo: investorspaces.com editorial
—— In This Article
Key Takeaways
- Small, recurring discretionary expenses often add up to hundreds of dollars monthly that could fund retirement contributions.
- Redirecting as little as $200 per month into a tax-advantaged account can meaningfully close a retirement savings gap over time.
- Automating the transfer of redirected funds removes the friction that causes most people to spend rather than save.
- IRS contribution limits for 401(k) and IRA accounts allow catch-up contributions for those aged 50 and older.
- Reviewing subscriptions, dining, and recurring service costs is the fastest way to find redirectable dollars.
Why redirecting spending works better than cutting it
Most retirement savings advice focuses on deprivation: spend less, sacrifice more. That framing tends to fail. Behavioral finance research consistently shows that broad spending cuts are hard to sustain because they create friction across daily life rather than targeting specific, low-regret expenses.
A more durable approach is redirection: identifying spending that delivers little real satisfaction and routing those dollars toward retirement contributions instead. The goal is not a stripped-down lifestyle. It is a deliberate trade between spending that goes unnoticed and saving that compounds over time.
This matters most during the middle earning years, when income is often at its peak but lifestyle creep quietly absorbs the difference. According to Bureau of Labor Statistics Consumer Expenditure Survey data, households in the 45-to-54 age range spend significant shares of income on food away from home, entertainment, and personal services. Many of those expenses are habitual rather than intentional.
Your savings rate has more influence on retirement readiness than most people realize. Redirecting even a modest slice of discretionary spending can shift that rate enough to close a meaningful gap.
What you will need before you start
Before working through the steps below, gather the following:
What you will need
Step-by-step: finding and redirecting discretionary dollars
Pull and categorize three months of transactions
Download statements from every account you use for spending: checking, credit cards, and any linked payment apps. Categorize each transaction into one of four buckets: fixed necessities (rent, mortgage, insurance), variable necessities (groceries, utilities), discretionary recurring (subscriptions, gym memberships, streaming), and discretionary one-off (dining out, retail, entertainment).
Most people underestimate their discretionary recurring total by 30 to 40 percent because individual charges are small and easy to overlook. The three-month window smooths out irregular purchases and gives a more honest monthly average.
Identify low-regret expenses
Go through your discretionary recurring and one-off categories and mark any item you would not actively miss if it disappeared. Common candidates include streaming services used less than twice a month, gym memberships replaced by free alternatives, auto-renewing software subscriptions, and premium tiers on apps where the free version is adequate.
Do not cut expenses you genuinely value. The goal is to surface spending that has become automatic rather than chosen. For most households, this exercise surfaces between $100 and $300 in monthly charges that no longer reflect real preferences.
Calculate a monthly redirection target
Add up the monthly total of your low-regret expenses. That figure is your starting redirection target. If the number is smaller than expected, also look at your variable discretionary spending. Reducing dining out by two or three meals per month or pulling back on retail subscriptions often adds another $50 to $100.
For context, the IRS sets annual 401(k) contribution limits (check the IRS website for the current year's figures), and those aged 50 and older can make additional catch-up contributions. Even if you cannot max out contributions, increasing them by your redirection amount moves the needle. A $200 monthly increase in a tax-deferred account can have a substantial cumulative effect over a decade, though actual outcomes depend on investment performance and are not guaranteed.
Cancel or downgrade the identified expenses
Work through your list systematically. For subscriptions, cancel directly through the provider's account settings rather than disputing charges later. For recurring services (lawn care, cleaning, premium delivery tiers), contact the provider or downgrade the plan. Set a two-week deadline to complete this step so it does not stall.
Track the exact monthly dollar amount freed up as you go. You need a specific number for the next step.
Increase your retirement contribution by the redirected amount
Log into your 401(k) plan portal or IRA provider and increase your contribution by the monthly amount you freed up. For a 401(k), this usually means adjusting your deferral percentage. For an IRA, set up a recurring monthly transfer for the same amount.
If your employer does not offer a retirement plan, open a traditional or Roth IRA and schedule the transfer to occur on the same day each month, ideally the day after your paycheck clears. Automating the transfer removes the decision entirely, which is the single most effective way to make the change stick.
Verify the change and document your baseline
Confirm the contribution change appears on your next pay stub or account statement. Then record your new monthly savings rate alongside your previous one. This gives you a concrete reference point for your annual review and makes the progress visible, which behavioral finance research links to sustained saving behavior.
You can also compare your current trajectory against retirement income targets using your plan's online calculator or a fee-only financial planner. Mid-career earners who document and revisit their savings rate regularly are more likely to increase it over time.
Once your redirected amount is flowing automatically, review it annually. Income changes, expenses shift, and everyday spending decisions compound in both directions over time. A once-a-year check keeps the process calibrated without turning it into a burden.
This article is for informational purposes only and is not personalized financial, tax, or investment advice. Consult a qualified financial adviser before making changes to your retirement contributions or investment strategy.
Budgeting & Saving Editorial Team
Budgeting & Saving Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile