
How Everyday Spending Decisions Shape Your Retirement Timeline
Small daily financial choices compound over decades. Learn how routine spending habits directly affect when and how comfortably you can retire.
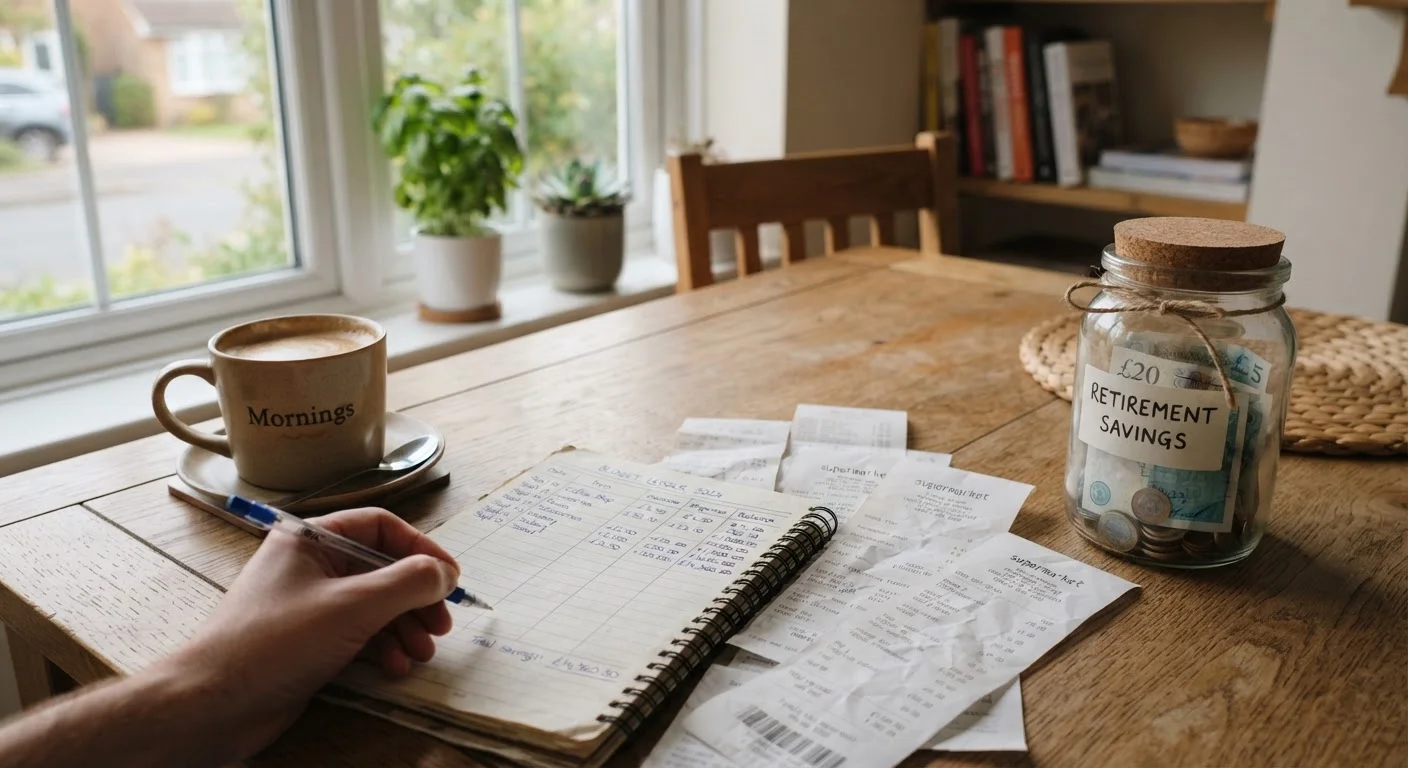
Photo: investorspaces.com editorial
—— In This Article
Key Takeaways
- Your savings rate matters more than your investment returns for determining retirement timing.
- Recurring subscriptions, high-interest debt, and underused insurance coverage are common spending leaks that reduce retirement contributions.
- Tax decisions made today, including withholding and account type choices, directly affect how much capital accumulates by retirement.
- Lifestyle creep after income increases is one of the most common ways retirement savings fall behind.
- Small redirections in spending, done consistently, compound into meaningful retirement portfolio growth over time.
The savings rate is the number that matters most
Most retirement planning conversations focus on investment returns, but research in personal finance consistently shows that your savings rate, how much of your gross income you actually set aside, has a larger effect on retirement timing than whether your portfolio gains 7 percent or 9 percent annually.
A household earning $90,000 per year that saves 15 percent reaches the same accumulation milestone significantly faster than one earning $110,000 but saving only 8 percent. The math is straightforward: a higher savings rate shortens the accumulation period and reduces the income replacement needed at retirement, because lower ongoing spending means a smaller nest egg can sustain the lifestyle.
Spending decisions set the savings rate. Every habitual purchase either fits within a budget that leaves room for saving or it does not. That is the direct link between daily choices and retirement timing. For a framework on how to structure spending across the years before retirement, see the decade-by-decade personal finance guide.
Check your savings rate, not just your balance
Your account balance tells you where you are. Your savings rate tells you how fast you are moving. Divide your annual retirement contributions (including employer match) by your gross income. If the result is below 10 to 15 percent, identify one recurring expense category where a reduction could move that number up. Even a 2-percentage-point increase sustained over a decade produces a measurable difference in retirement timing.
Debt payments are retirement contributions you are not making
Carrying consumer debt, particularly revolving credit card balances at 20 percent or more annual interest, redirects a share of monthly cash flow away from any asset-building purpose. A household paying $400 per month in credit card interest is not just spending $400; it is forgoing the compounded growth that $400 invested monthly would produce over 15 to 20 years.
The same logic applies to car loans, personal loans, and any high-rate obligation. Paying these down aggressively is not separate from retirement planning; it is part of it. Once high-interest debt is cleared, the freed cash flow can shift directly to retirement accounts.
Mortgage debt is a different calculation. A low fixed-rate mortgage may be worth carrying closer to retirement if the after-tax interest rate falls below realistic long-term portfolio return expectations, but that is a decision best made with a licensed financial adviser who can model your specific numbers. For more on which obligations to clear first, see debt before retirement: which balances to clear first.
~15%
Savings rate recommended by many financial planners
Fidelity and other major retirement research sources suggest saving at least 15 percent of gross income, including any employer match, to maintain pre-retirement living standards.
43%
Working-age Americans with no retirement savings
The Federal Reserve's Survey of Consumer Finances has consistently found that a large share of working-age households hold no retirement account assets at all.
$1,000
Monthly spending reduction needed to retire 3 years earlier
Financial planning modeling generally shows that reducing monthly expenses by around $1,000 and redirecting that amount to savings can meaningfully shorten a retirement timeline, depending on starting age and portfolio size.
Tax choices now change portfolio size later
Routine tax decisions affect how much capital you accumulate. Contributing to a traditional 401(k) reduces taxable income today, leaving more money compounding inside the account. A Roth IRA or Roth 401(k), by contrast, uses after-tax dollars but produces tax-free growth, which can be more valuable if your tax rate in retirement is expected to be higher.
Beyond account type, withholding accuracy matters. Systematically over-withholding means giving the IRS an interest-free loan each year instead of investing that money throughout the year. Adjusting your W-4 to a more accurate level and directing the difference to a retirement account is a low-friction change with a real long-term effect.
Withdrawal sequencing in retirement also affects portfolio longevity. Drawing from taxable accounts first, then tax-deferred, then tax-free is a common strategy, though the optimal order depends on your bracket situation each year. The tax-efficient withdrawal strategies guide covers this in detail.
Lifestyle creep and the retirement gap it creates
Income growth is not automatically retirement progress. When every raise is absorbed by higher rent, newer vehicles, upgraded subscriptions, or more frequent dining out, the savings rate stays flat or falls. This pattern is lifestyle creep, and it is common precisely because each individual upgrade feels modest relative to the new income level.
The retirement consequence is that spending expectations at the time of retirement are now higher, requiring a larger portfolio to sustain them, while the rate of accumulation has not increased proportionally. The gap between what was saved and what is needed widens from both directions.
Tracking how your savings rate changes after each income increase is more useful than tracking the dollar amount saved. If a raise does not move the savings rate up, the money is being absorbed somewhere. The lifestyle creep and its retirement impact article offers a practical method for measuring and correcting this drift.
For readers who want to identify specific spending leaks and redirect them efficiently, closing the retirement gap by redirecting spending provides concrete steps. Setting up automatic contributions before discretionary spending can interfere is covered in automating your savings.
This article is for informational purposes only and does not constitute personalized financial, tax, or investment advice. Consult a qualified financial adviser, accountant, or attorney before making decisions based on your individual circumstances.
Frequently Asked Questions
Personal Finance Editorial Team
Personal Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile