
Tax-Efficient Withdrawal Strategies for Retirement Accounts
Sequencing withdrawals from taxable, tax-deferred, and tax-free accounts can meaningfully reduce your lifetime tax bill. Here is how the logic works.
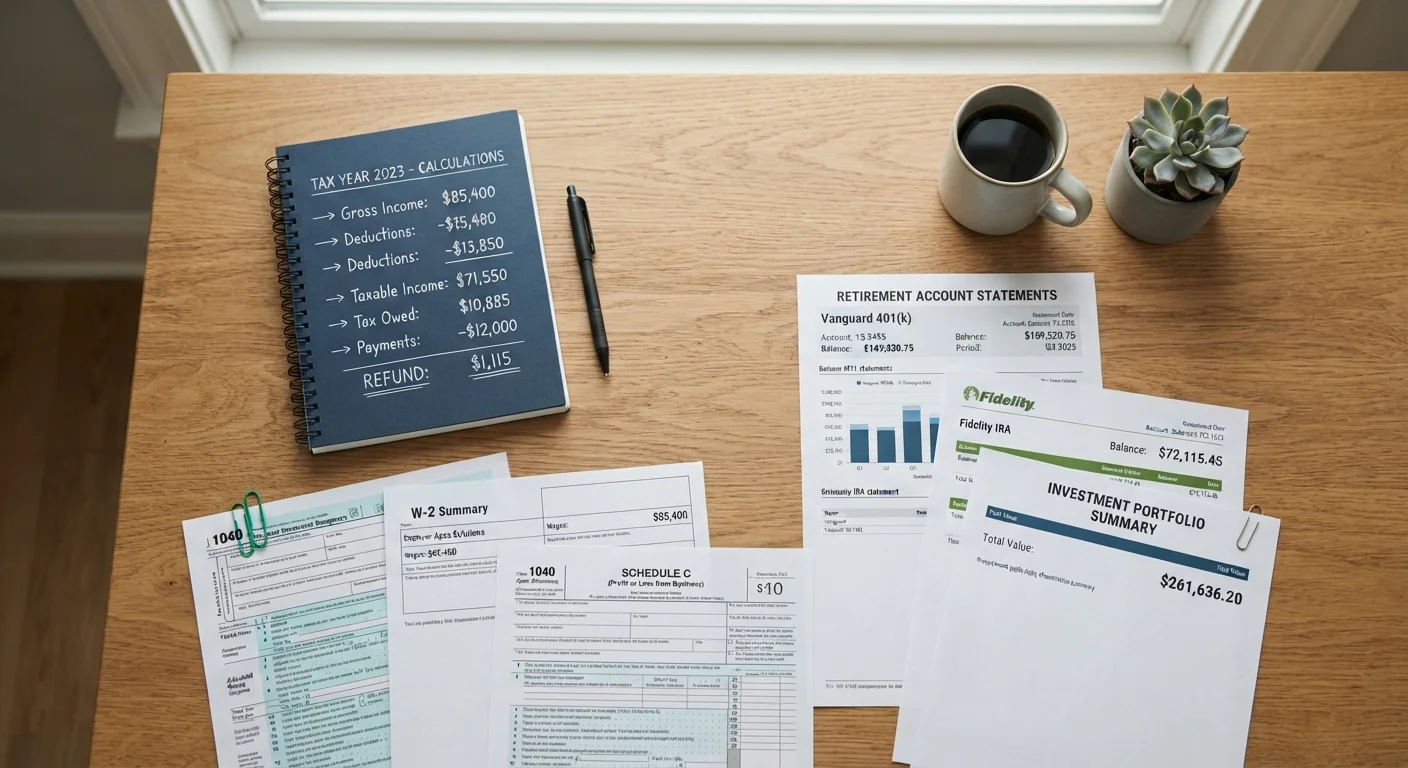
Photo: investorspaces.com editorial
—— In This Article
Key Takeaways
- Withdrawing from taxable, tax-deferred, and tax-free accounts in a deliberate sequence can reduce your lifetime tax burden.
- Required Minimum Distributions from traditional IRAs and 401(k)s can push retirees into higher tax brackets if not planned ahead.
- Roth conversions in low-income years before RMDs begin are a proven tactic for managing future taxable income.
- Coordinating Social Security timing with account withdrawals can prevent unnecessary taxation of benefits.
- Each retiree's optimal sequence depends on current income, projected future income, and estate goals.
Why withdrawal order matters
Most retirees hold assets in three types of accounts: taxable brokerage accounts, tax-deferred accounts (traditional IRAs and 401(k)s), and tax-free accounts (Roth IRAs and Roth 401(k)s). Each type carries a different tax treatment when money comes out, and drawing them down in the wrong order can quietly add tens of thousands of dollars to your lifetime tax bill.
Taxable accounts generate capital gains taxes only on growth. Tax-deferred accounts produce ordinary income tax on every dollar withdrawn. Tax-free Roth accounts produce no federal tax on qualified distributions. Because these rates differ, the sequence in which you tap each bucket determines how much of your savings you actually keep.
A common default is to spend taxable accounts first, then tax-deferred, then Roth. That approach is reasonable as a starting point, but it ignores the value of deliberately filling lower tax brackets, managing Required Minimum Distributions (RMDs), and preserving Roth assets for heirs. See our guide to maximizing tax-advantaged savings after 50 for context on how pre-retirement decisions affect these balances.
Understanding the three account buckets
Taxable accounts hold assets such as stocks, bonds, and mutual funds purchased through a standard brokerage. Dividends and interest are taxed annually; when you sell, you owe capital gains tax on the appreciation. Long-term capital gains rates (for assets held over one year) are 0%, 15%, or 20% depending on income, which is often lower than ordinary income rates.
Tax-deferred accounts include traditional IRAs and traditional 401(k)s. Contributions were made pre-tax, so every withdrawal is taxed as ordinary income. The IRS requires you to begin taking RMDs from these accounts starting at age 73 (under current law following the SECURE 2.0 Act). Failing to take an RMD triggers a penalty equal to 25% of the amount not withdrawn, reduced to 10% if corrected promptly.
Tax-free accounts are Roth IRAs and Roth 401(k)s. Contributions were made with after-tax dollars, qualified withdrawals are completely tax-free, and Roth IRAs have no RMD requirement during the owner's lifetime. These features make Roth balances particularly valuable late in retirement and for legacy planning.
The 0% capital gains bracket is often overlooked
Federal law sets the long-term capital gains rate at 0% for taxpayers whose taxable income falls within the 10% or 12% ordinary income brackets. In retirement, when wages drop and income becomes more controllable, many retirees can harvest gains in taxable accounts at no federal cost. State taxes may still apply, so check your state's treatment before acting.
Step-by-step withdrawal sequencing
The steps below describe a general framework. Your optimal sequence will differ based on your income sources, tax bracket, Social Security strategy, and estate objectives. Work with a qualified tax adviser or financial planner before implementing any strategy.
Map your income sources and current tax bracket
List every income source: Social Security, pensions, rental income, part-time work, and investment income. Determine your current marginal federal tax rate and estimate your taxable income before any discretionary withdrawals. This baseline tells you how much room you have in your current bracket before a withdrawal pushes you into a higher one.
Identify your RMD obligations
Calculate the RMDs you are legally required to take from each traditional IRA and 401(k). Your custodian can provide these figures, or you can calculate them using the IRS Uniform Lifetime Table and each account's prior December 31 balance. RMDs are a floor, not a ceiling: you can always withdraw more, but you must at minimum satisfy the requirement.
Fill lower tax brackets with Roth conversions
In years when your taxable income is below the top of the 12% or 22% federal bracket (or whichever bracket is lower than your expected future rate), consider converting a portion of your traditional IRA to a Roth IRA. The converted amount is taxed as ordinary income in the year of conversion, but future growth and withdrawals from that Roth balance are tax-free. This is most powerful in the gap years between retirement and age 73, when RMDs have not yet begun and income may be at its lowest.
Draw taxable accounts for near-term spending
For day-to-day retirement expenses, taxable brokerage accounts are often the right first source because long-term capital gains rates are lower than ordinary income rates for most retirees. Selling appreciated positions in taxable accounts while staying within the 0% capital gains bracket (which applies to taxpayers in the 10% or 12% ordinary income brackets) effectively produces tax-free income from those assets.
Reserve Roth accounts for flexibility and legacy
Roth IRAs carry no lifetime RMD requirement and pass to heirs income-tax-free (subject to the 10-year distribution rule for most non-spouse beneficiaries under the SECURE 2.0 Act). Preserving Roth balances as long as possible keeps a tax-free reserve available for large unexpected expenses, high-income years, or as part of an estate plan. Spending Roth money last maximizes the tax-free compounding period and the after-tax value passed to heirs.
Revisit your sequence annually
Tax law, account balances, income needs, and personal circumstances all change. Review your withdrawal plan each year before making large distributions. Changes in tax brackets, Social Security benefit timing, or a major medical expense can all shift the optimal sequence. An annual review with a fee-only financial planner or CPA keeps the strategy current. If you are still in the accumulation phase, automating contributions to each account type builds the diversified tax bucket structure that makes this sequencing possible.
Common pitfalls and adjustments
The conventional sequence breaks down when large RMDs collide with Social Security benefits and other income. Up to 85% of Social Security benefits become taxable when combined income (adjusted gross income plus nontaxable interest plus half of Social Security benefits) exceeds certain thresholds. Retirees who delay tapping tax-deferred accounts while their balances grow can face RMDs large enough to push them into a higher bracket and increase Social Security taxation simultaneously.
Medicare premiums add another layer. Income-Related Monthly Adjustment Amounts (IRMAA) apply to Medicare Parts B and D when modified adjusted gross income exceeds set thresholds (which the IRS adjusts periodically). A large Roth conversion or an unusually high-withdrawal year can trigger IRMAA surcharges that persist for two years.
Coordinating the timing of large withdrawals, conversions, and asset sales across a two-year look-back window takes careful planning. Spending decisions made years before retirement shape how much flexibility you have in these later years. Consider tax-loss harvesting in taxable accounts to offset gains, and use charitable qualified distributions from IRAs to satisfy RMDs without recognizing taxable income if philanthropy is part of your plan.
Wealth Management Editorial Team
Wealth Management Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile