
Growth Investing vs. Value Investing: Two Approaches to Picking Equities
Understand the core philosophies behind growth and value investing and how each approach fits different retirement timelines.
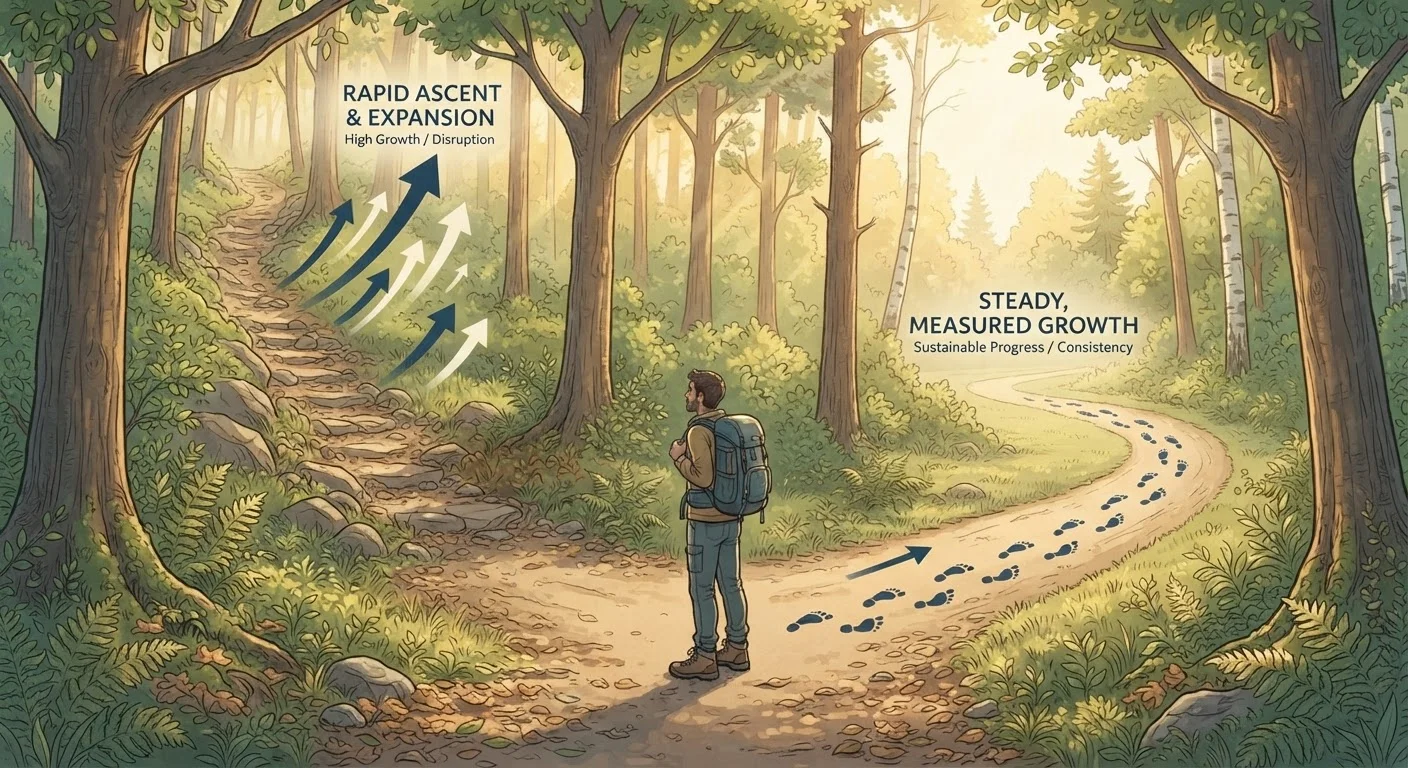
Photo: investorspaces.com editorial
—— In This Article
Key Takeaways
- Growth investing targets companies expected to expand earnings faster than the overall market.
- Value investing focuses on stocks priced below what fundamental analysis suggests they are worth.
- Growth stocks tend to carry higher valuations and greater short-term price swings.
- Value stocks may offer more downside cushion but can stay underpriced for extended periods.
- Neither approach consistently outperforms the other across all market environments.
- Your retirement timeline and tolerance for volatility should guide how you weight each philosophy.
What separates growth from value
Growth investing and value investing start from different questions. A growth investor asks: which companies will expand their revenues and earnings substantially faster than average? A value investor asks: which companies are priced below what their fundamentals actually justify?
Growth investors accept high price-to-earnings (P/E) ratios because they expect future profits to catch up to today's stock price. Technology and healthcare firms are common examples where investors pay a premium for anticipated expansion. Value investors do the opposite: they search for stocks with low P/E or price-to-book ratios, reasoning that the market has temporarily mispriced a fundamentally sound business.
Before going further, a quick note on terminology: the P/E ratio compares a stock's price to its earnings per share. A high P/E means investors are paying more for each dollar of earnings, often because they expect those earnings to grow quickly. If these terms are new, the investing terms reference glossary covers them in plain language.
Risk and return characteristics
Growth stocks typically trade at elevated valuations, which makes them more sensitive to changes in interest rates and investor sentiment. When a company reports earnings even slightly below expectations, the stock price can drop sharply. This volatility is manageable over a 20-year retirement horizon, but it can be damaging if a large drawdown coincides with when you need to start withdrawing funds.
Value stocks are not automatically safe. A cheap stock is sometimes cheap because the business has genuine problems, a scenario called a "value trap." The discipline in value investing is distinguishing between a stock that is temporarily out of favor and one whose earnings power has permanently declined.
| Criterion | Growth investing | Value investing |
|---|---|---|
| Core focus | Future earnings expansion | Current price vs. intrinsic worth |
| Typical P/E ratio | Higher than market average | Lower than market average |
| Short-term volatility | Generally higher | Generally lower |
| Main risk | Earnings disappoint lofty expectations | Stock is cheap because business is declining |
| Income from dividends | Often minimal or none | More common, though not guaranteed |
| Suits investors who... | Have a long horizon and high risk tolerance | Want a margin of safety and patience to wait |
Over long periods, academic research has found that value stocks have historically produced competitive returns, though growth stocks led for extended stretches, particularly in the decade following the 2008 financial crisis. Past performance does not guarantee future results, and both styles move in and out of favor depending on the economic environment.
For a broader look at how style choices fit within a full portfolio, see asset allocation fundamentals for long-term investors.
Applying each approach to a retirement timeline
Retirement planning introduces a time dimension that pure stock analysis ignores. A 45-year-old with 20 years until retirement can absorb several market cycles and still benefit from compounding, making a heavier growth allocation reasonable. A 58-year-old with a shorter horizon faces sequence-of-returns risk: a steep decline in the years just before or after retirement can permanently reduce sustainable withdrawal amounts.
Value-oriented holdings tend to have lower starting valuations, which can cushion a portfolio during broad market sell-offs, though this is not guaranteed. Many retirement investors blend both styles, adjusting the ratio as they age. This is consistent with the general principle of gradually shifting toward less volatile assets as retirement approaches.
One common misconception is that growth investing is always aggressive and value investing is always conservative. In practice, a poorly diversified growth portfolio and a well-diversified value portfolio can have very different risk profiles. Common investing misconceptions that can derail retirement plans covers several of these faulty assumptions in detail.
This article is for informational purposes only and does not constitute personalized investment advice. Consult a licensed financial adviser before making decisions about your own portfolio.
Investing Basics Editorial Team
Investing Basics Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile