
Asset Allocation Fundamentals for Long-Term Investors
Learn how dividing your portfolio across different asset classes can help manage risk and support steady growth over time.
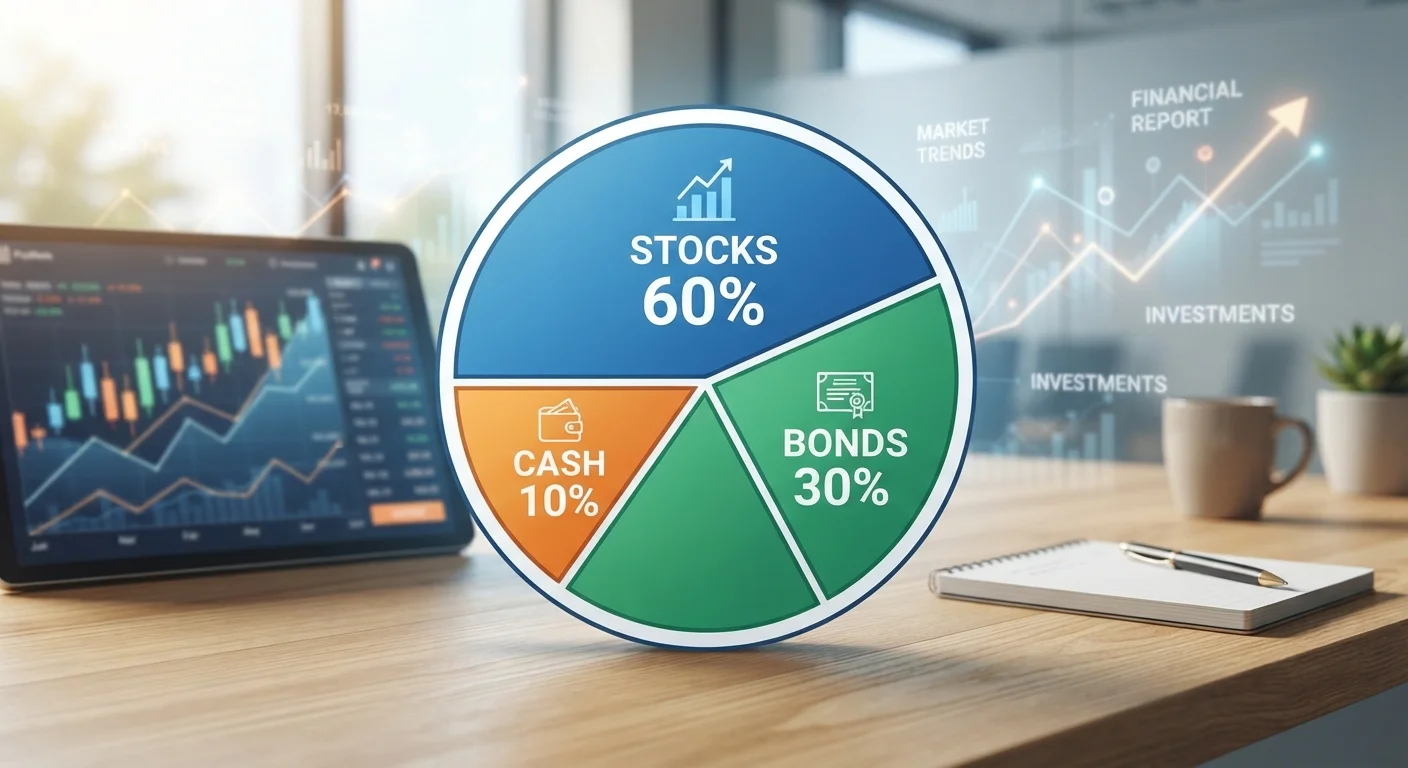
Photo: investorspaces.com editorial
—— In This Article
Key Takeaways
- Asset allocation is the decision of how to divide a portfolio among different asset classes.
- Stocks, bonds, and cash each behave differently, which is why holding a mix can reduce overall volatility.
- Time horizon is one of the strongest inputs to an appropriate allocation: longer timelines can generally absorb more short-term loss.
- Diversification does not eliminate risk, but it can limit the damage any single investment can do to a portfolio.
- Allocation decisions should be revisited periodically, especially as retirement approaches.
What asset allocation means
Asset allocation is the decision of how to divide a portfolio among different categories of investments. Those categories, called asset classes, typically include stocks (equities), bonds (fixed income), and cash or cash equivalents. Each class has a different risk and return profile, and they tend not to move in lockstep with one another.
Because the classes behave differently, combining them can reduce the overall volatility of a portfolio without necessarily sacrificing all of the growth potential that comes from riskier assets. This is the core idea behind modern portfolio theory, a framework developed to show that a well-constructed mix can be more efficient than any single asset held alone.
Asset allocation is not a one-time decision. As your financial situation, goals, and time horizon change, the appropriate mix shifts with them. Treating it as a fixed setting is one of the most common mistakes long-term investors make.
Asset class
A broad category of investments that share similar characteristics and tend to behave similarly in the market. Common classes include stocks, bonds, and cash.
Diversification
Spreading investments across many different securities or asset classes so that poor performance in one area does not dominate the portfolio.
Time horizon
The length of time an investor expects to hold a portfolio before needing the money. Longer horizons can generally tolerate more short-term volatility.
Volatility
The degree to which an investment's price fluctuates over time. Higher volatility means larger swings in value, both up and down.
Glide path
A gradual shift in asset allocation over time, typically moving from a higher proportion of stocks toward more bonds and cash as retirement approaches.
Systematic risk
Risk that affects the entire market and cannot be eliminated through diversification. Economic recessions and interest rate changes are common sources.
The main asset classes
Stocks represent ownership in a company. They offer the highest long-term growth potential among the main asset classes, but they also carry the most short-term volatility. A stock's price can fall sharply in a market downturn and recover over years, which is why time horizon matters so much when deciding how much stock exposure to hold.
Bonds are loans made to governments or corporations. In return, the borrower pays periodic interest and returns the principal at a set date. Bonds generally produce lower returns than stocks over long periods, but they tend to hold value better during equity downturns, providing a stabilizing effect in a mixed portfolio.
Cash and cash equivalents, such as money market funds or short-term Treasury bills, carry the least risk but also the lowest return. They preserve capital and provide liquidity, which can be useful as retirement draws near or when funds may be needed on short notice.
Funds, including mutual funds and exchange-traded funds, pool money from many investors to buy a collection of securities. They are not a separate asset class but a vehicle for holding stocks, bonds, or both. See what stocks, bonds, and funds each contribute to a portfolio for a deeper look at how each one functions.
How time horizon shapes your mix
Time horizon is the length of time before you expect to need the money you are investing. It is one of the most practical inputs to an allocation decision because it determines how much short-term volatility you can realistically absorb.
An investor with 25 years until retirement has time to ride out market downturns and wait for recoveries. That longer runway generally supports a higher allocation to stocks. An investor five years from retirement has less time to recover from a significant loss, which is why many financial frameworks suggest gradually shifting toward a larger share of bonds and cash as retirement nears.
This gradual shift is sometimes called a glide path. Target-date funds are designed around this concept, automatically adjusting their allocation over time toward a more conservative mix as the target retirement year approaches. Understanding the glide path within any fund you hold is worth doing, because funds with the same target date can have notably different stock-to-bond ratios.
Risk and diversification
Every investment carries some risk. The relevant question is which risks you are taking, and whether they match your situation. Two broad categories of risk matter most for allocation decisions.
Market risk, sometimes called systematic risk, affects the entire market or a broad asset class and cannot be removed by holding more securities. A global economic contraction, for example, tends to push most stock prices down regardless of which companies you own.
Unsystematic risk, or company-specific risk, affects individual securities. Owning shares in a single company means that company's failures fall entirely on your portfolio. Spreading holdings across many companies, sectors, and geographies reduces this type of risk substantially.
Diversification works within and across asset classes. Within stocks, holding domestic and international equities, across sectors like technology, healthcare, and consumer goods, reduces the damage any single position can do. Across asset classes, pairing stocks with bonds means a sharp drop in equities may be partially offset by bond stability. For a closer look at how personal loss tolerance should inform these decisions, see how risk tolerance shapes a retirement portfolio.
Check your actual allocation periodically
Strong stock market returns can push your equity percentage well above your original target without any action on your part. Reviewing your allocation once a year takes only a few minutes and can reveal drift that has meaningfully changed your risk exposure. Many brokerage platforms display your current allocation breakdown in the account overview.
Putting it into practice
A reasonable starting point is to identify your time horizon and your genuine tolerance for watching your portfolio value drop without selling. Those two inputs together do more to define an appropriate allocation range than any rule of thumb alone.
From there, consider how your current holdings map to the major asset classes. If stocks have grown significantly over recent years, your portfolio may now hold a larger share of equities than you originally intended. This drift is normal, and correcting it is what rebalancing addresses. When and how to rebalance a portfolio walks through the mechanics in detail.
If you are interested in how stock selection fits into a broader allocation framework, growth investing versus value investing covers how different equity approaches suit different timelines and goals.
Allocation decisions involve trade-offs that depend heavily on individual circumstances. A licensed financial adviser can help you translate general principles into a plan suited to your income, obligations, and goals.
This article is for informational and educational purposes only. It is not personalised financial, investment, tax, or legal advice. Past performance does not guarantee future results. Consult a qualified financial professional before making decisions about your own portfolio.
Frequently Asked Questions
Investing Basics Editorial Team
Investing Basics Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile