
The Real Cost of Carrying a Mortgage Into Retirement
A mortgage in retirement is not automatically a problem, but it does change cash flow dynamics. Here is what to weigh before making that decision.
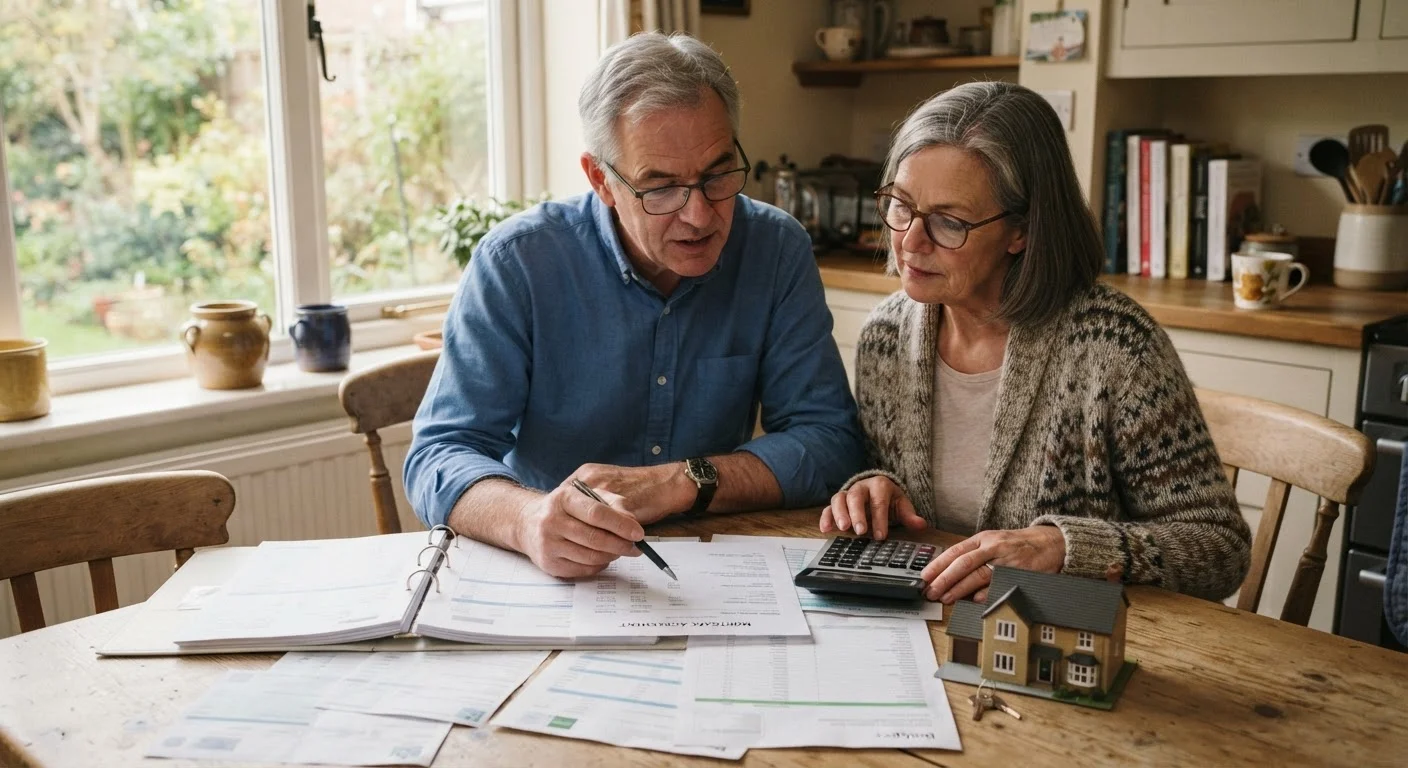
Photo: investorspaces.com editorial
—— In This Article
Key Takeaways
- A mortgage in retirement is not automatically harmful, but it does reduce monthly cash flow flexibility.
- The mortgage interest deduction provides less benefit for many retirees than commonly assumed.
- Paying off a mortgage early has an opportunity cost if investment returns exceed the loan interest rate.
- Sequence-of-returns risk makes fixed housing payments more consequential in early retirement years.
- Your decision should account for income sources, tax situation, and overall debt picture together.
Preserves liquid capital for investment growth
Deploying savings toward investments rather than mortgage payoff keeps money accessible and potentially growing. This matters most when the loan rate is meaningfully below expected long-term portfolio returns.
Maintains financial flexibility in emergencies
Retirees who keep liquid savings rather than paying off a mortgage can cover unexpected expenses without forced portfolio withdrawals or taking on new debt at higher rates.
Fixed-rate loans protect against inflation
A fixed monthly payment loses real value over time as inflation rises. In an inflationary environment, the real cost of that payment declines each year while the home's value may increase.
Avoids triggering a large taxable event
Liquidating a traditional IRA or 401(k) to pay off a mortgage generates ordinary income in the year of withdrawal, which can push a retiree into a higher tax bracket or affect Medicare premium calculations.
Fixed payment reduces monthly cash flow flexibility
A mandatory debt payment limits how much retirees can cut spending during a market downturn or health event. Flexibility in retirement spending is a genuine buffer against financial stress.
Increases sequence-of-returns risk exposure
When early retirement coincides with a portfolio decline, a fixed housing payment forces continued withdrawals at depressed asset prices, compounding the damage to long-term portfolio longevity.
Interest deduction rarely offsets true carrying cost
Most retirees with smaller loan balances cannot itemize above the standard deduction, meaning they pay the full nominal interest rate with no tax offset. The math favors payoff more often than borrowers expect.
Ongoing costs compound beyond principal and interest
Property taxes, homeowner's insurance, and maintenance do not disappear with a paid-off house, but eliminating principal and interest still removes the largest portion of monthly housing obligation.
Why this question matters more than it used to
Homeowners are entering retirement with mortgage debt at higher rates than previous generations. According to the Consumer Financial Protection Bureau, the share of homeowners aged 65 and older carrying mortgage debt roughly doubled between 1989 and the mid-2010s, and balances have grown in real terms. That shift means the decision to pay off a home before retiring is no longer a default; it requires deliberate analysis.
The stakes are real. A $1,500 monthly mortgage payment that felt routine on a working salary may consume 20 percent or more of a retiree's take-home income. That compression affects everything from discretionary spending to the ability to absorb a medical expense or a market downturn without selling investments at a loss. See how spending patterns shift across retirement to understand how housing costs fit into the broader picture.
The case for keeping the mortgage
Preserves liquid capital for investment growth
Deploying savings toward investments rather than mortgage payoff keeps money accessible and potentially growing. This matters most when the loan rate is meaningfully below expected long-term portfolio returns.
Maintains financial flexibility in emergencies
Retirees who keep liquid savings rather than paying off a mortgage can cover unexpected expenses without forced portfolio withdrawals or taking on new debt at higher rates.
Fixed-rate loans protect against inflation
A fixed monthly payment loses real value over time as inflation rises. In an inflationary environment, the real cost of that payment declines each year while the home's value may increase.
Avoids triggering a large taxable event
Liquidating a traditional IRA or 401(k) to pay off a mortgage generates ordinary income in the year of withdrawal, which can push a retiree into a higher tax bracket or affect Medicare premium calculations.
The core argument for retaining a low-rate mortgage is capital preservation. Paying off a 3.5 percent fixed mortgage by liquidating a portfolio earning more than that rate over time means trading a higher-returning asset for a guaranteed return equal to the loan rate. Whether that trade makes sense depends on your specific interest rate, your tax bracket, and how your portfolio is allocated.
Liquidity also matters. Home equity is not easily accessed in an emergency. Retirees who deplete savings to pay off a mortgage may face a cash crunch when a furnace fails or a health cost arises, forcing them to withdraw from tax-deferred accounts at an inopportune time or take on higher-cost debt. Keeping the mortgage and maintaining a liquid reserve avoids that bind.
The case for paying it off before you retire
Fixed payment reduces monthly cash flow flexibility
A mandatory debt payment limits how much retirees can cut spending during a market downturn or health event. Flexibility in retirement spending is a genuine buffer against financial stress.
Increases sequence-of-returns risk exposure
When early retirement coincides with a portfolio decline, a fixed housing payment forces continued withdrawals at depressed asset prices, compounding the damage to long-term portfolio longevity.
Interest deduction rarely offsets true carrying cost
Most retirees with smaller loan balances cannot itemize above the standard deduction, meaning they pay the full nominal interest rate with no tax offset. The math favors payoff more often than borrowers expect.
Ongoing costs compound beyond principal and interest
Property taxes, homeowner's insurance, and maintenance do not disappear with a paid-off house, but eliminating principal and interest still removes the largest portion of monthly housing obligation.
A paid-off home converts a fixed monthly obligation into an optional expense. That matters when income is less predictable. If a market downturn hits in the first few years of retirement, a retiree with no mortgage payment has far more room to cut spending than one committed to a fixed debt service. This is sometimes called sequence-of-returns risk: early portfolio losses are especially damaging because withdrawals lock in those losses before any recovery.
There is also a psychological dimension that financial planning sometimes underweights. Knowing housing costs are covered regardless of market conditions or interest rate changes removes a category of financial anxiety that affects real spending behavior. That is not a trivial benefit, even if it is harder to quantify. For a broader look at how debt affects retirement readiness, prioritizing which balances to clear first is a practical starting point.
Refinancing is a separate decision
If you carry a mortgage into retirement, the loan terms matter as much as the balance. An adjustable-rate mortgage introduces payment variability that is harder to manage on fixed income. Retirees holding variable-rate loans should evaluate whether refinancing to a fixed rate makes sense given remaining balance, time horizon, and closing costs. That calculation is distinct from whether to pay off the loan entirely.
The mortgage interest deduction is worth less than many expect
Many homeowners overestimate the tax benefit of carrying a mortgage in retirement. The Tax Cuts and Jobs Act of 2017 raised the standard deduction substantially. For the 2024 tax year, the standard deduction for a married couple filing jointly is $29,200, with an additional amount available for those aged 65 and older. A retiree would need total itemized deductions to exceed that figure before the mortgage interest generates any marginal tax benefit.
For many retirees with smaller loan balances and relatively low interest payments, itemizing no longer makes financial sense. If the deduction is not in play, the after-tax cost of the mortgage equals the full nominal rate. That changes the math on whether keeping the mortgage and investing the difference actually comes out ahead.
2x
Growth in older homeowners carrying mortgage debt
The Consumer Financial Protection Bureau reported that the share of homeowners 65 and older with mortgage debt approximately doubled between 1989 and the mid-2010s.
$29,200
Standard deduction for married filers in 2024
For the 2024 tax year, the IRS standard deduction for married couples filing jointly means most retirees with modest mortgage balances receive no marginal tax benefit from keeping the loan.
20%+
Share of retirement income a typical mortgage can consume
A moderate mortgage payment that was manageable on a working salary can represent a fifth or more of monthly retirement income, meaningfully constraining discretionary spending.
How to evaluate your own situation
No formula applies universally, but a few concrete questions sharpen the analysis. First, what are your reliable income sources in retirement: Social Security, a pension, required minimum distributions? If those sources cover essential expenses with room to spare, a mortgage payment is more manageable. If income is variable or drawn largely from a portfolio, a fixed obligation adds risk.
Second, what is the interest rate on the loan? A 6.5 percent mortgage held in a conservative retirement portfolio looks very different from a 2.75 percent loan held against a diversified portfolio. Third, how much of your net worth is tied up in home equity versus liquid assets? Retirees with most of their wealth in the house and modest savings face a different calculus than those with substantial investment accounts.
These questions connect directly to retirement cash flow planning. Daily spending choices compound over time, and the mortgage decision is one of the largest single levers available in the years before retirement. A fee-only financial planner or a certified public accountant can model the after-tax outcomes specific to your income, bracket, and balance sheet. General information like this article cannot substitute for that analysis.
This article is for general informational purposes only and does not constitute personalized financial, tax, or legal advice. Consult a qualified financial adviser or tax professional before making decisions about mortgage payoff, retirement income, or investment strategy.
Personal Finance Editorial Team
Personal Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile