
Tax Efficiency in Personal Finance: Keeping More of What You Earn
Taxes quietly erode wealth over time. Explore general strategies for organising finances in a tax-aware way to protect long-term retirement savings.
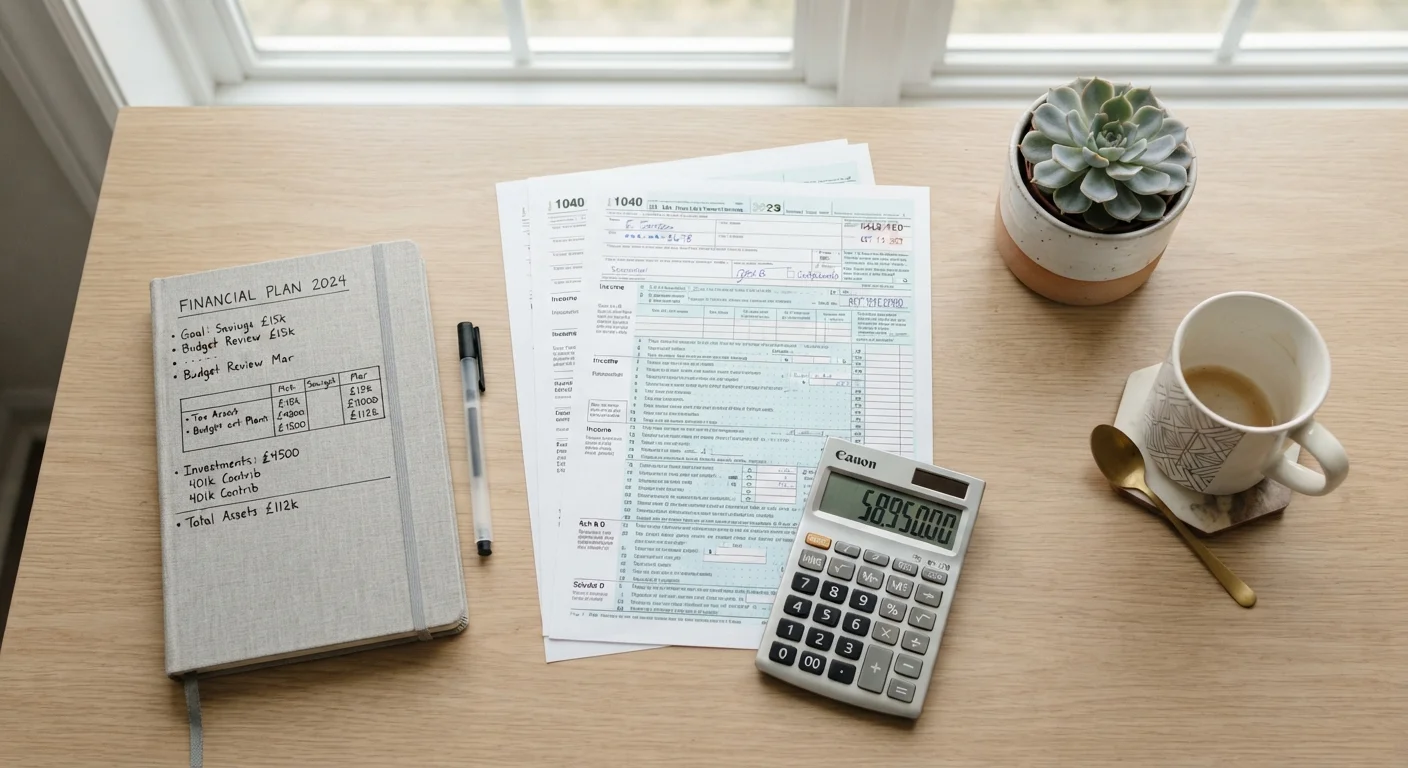
Photo: investorspaces.com editorial
—— In This Article
Key Takeaways
- Tax drag on investments compounds silently over decades, making tax-aware account placement a high-leverage habit.
- Contributing to tax-advantaged accounts is one of the most effective ways to reduce your current or future tax burden.
- Sequencing which accounts you draw from in retirement can significantly lower your lifetime tax bill.
- Coordinating deductions, charitable giving, and capital gains realisation requires planning across multiple years, not just at tax time.
How taxes quietly shrink long-term wealth
Most people focus on gross income and investment returns. What lands in their accounts after taxes is a different number, and the gap widens every year. A portfolio generating a 7% annual return before taxes may net considerably less, depending on account type, asset class, and how gains are realised. Over a 20- or 30-year horizon, that difference can amount to a substantial share of a retirement nest egg.
Tax efficiency is not a niche concern for high earners. It matters to anyone who saves, invests, or carries debt, because every dollar paid unnecessarily to taxes is a dollar that no longer compounds. The strategies below are not a substitute for advice from a licensed tax professional or financial adviser, who can apply them to your specific situation. They are general principles that apply broadly across income levels and life stages.
For a broader look at the financial habits that protect retirement readiness, see habits mid-career earners often overlook.
Core practices for tax-efficient personal finance
These practices address the decisions most people make repeatedly, from annual contribution choices to how they hold different assets.
Maximise contributions to tax-advantaged accounts before investing in taxable accounts.
Traditional 401(k) and IRA contributions reduce taxable income in the year they are made. Roth contributions do not reduce current taxes, but qualified withdrawals in retirement are tax-free. Either way, the tax treatment is more favourable than a standard brokerage account, where gains are taxed as they are realised.
Place less tax-efficient assets in tax-advantaged accounts and more tax-efficient assets in taxable accounts.
Not all investments generate the same type of taxable event. Bonds pay interest taxed as ordinary income; broadly diversified index funds in taxable accounts generate mostly long-term capital gains and qualified dividends, which are taxed at lower rates. Placing bonds and actively managed funds inside a tax-deferred account reduces the annual tax drag on those holdings.
Harvest capital losses to offset capital gains in taxable accounts.
When an investment in a taxable account has declined in value, selling it locks in a loss that can offset capital gains realised elsewhere in the same tax year. Losses exceeding gains can offset up to $3,000 of ordinary income annually, with any remaining amount carried forward. This does not eliminate tax liability permanently, but it defers it and frees capital for redeployment.
Time the realisation of capital gains to align with lower-income years.
Long-term capital gains are taxed at 0%, 15%, or 20% depending on total taxable income. In years when income is lower, such as early retirement before Social Security begins or after a job change, there may be room to realise gains at the 0% rate. This window is predictable and worth planning for in advance.
Bundle deductible expenses into a single tax year to exceed the standard deduction when it makes sense.
The standard deduction is fixed for each filing status, and itemising is only beneficial when deductible expenses exceed it. Some deductible expenses, including charitable contributions and certain medical costs, can be timed or grouped. This technique, sometimes called bunching, allows a taxpayer to itemise in alternating years and take the standard deduction in others.
Tax efficiency does not require complexity. Most of the gains come from applying a small number of principles consistently over many years. The budgeting and saving fundamentals that support these practices are covered in detail across our library.
Quick actions you can take now
Some tax-efficiency improvements take years to fully execute. Others can be done this week. The following actions have a measurable effect with relatively little friction.
If you are within ten years of retirement, the stakes of these decisions rise. A pre-retirement audit can help you identify which gaps remain before you stop working.
Tax efficiency and retirement income planning
During the accumulation phase, the main goal is to reduce the taxes owed on income and investment growth. Once retirement begins, the goal shifts to managing how and when that money is withdrawn. The two phases require different thinking, and the decisions made during working years directly constrain the options available later.
Holding assets across taxable brokerage accounts, traditional (pre-tax) retirement accounts, and Roth (after-tax) accounts gives you flexibility to draw from the most tax-advantaged source in any given year. That flexibility is only available if you build it in advance. Tax-efficient withdrawal strategies covers the sequencing logic in detail.
Charitable giving also intersects with tax planning. Donor-advised funds, qualified charitable distributions from IRAs after age 70.5, and appreciated asset donations each carry distinct tax treatment. For retirees interested in legacy planning, legacy-building approaches outlines how giving vehicles fit into a broader financial plan.
Tax planning connects to wealth preservation more broadly. Inflation and sequence-of-returns risk can erode real purchasing power even when nominal balances look stable. What wealth preservation means in retirement addresses both risks with context that complements tax-aware strategies.
This article is for informational purposes only and does not constitute personalised tax, investment, or legal advice. Consult a qualified tax professional or financial adviser for guidance specific to your circumstances.
Personal Finance Editorial Team
Personal Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile