
Fixed Expenses vs. Variable Expenses: Where Retirement Savings Really Hide
Understanding the difference between fixed and variable costs reveals which spending categories offer the most room to save more.
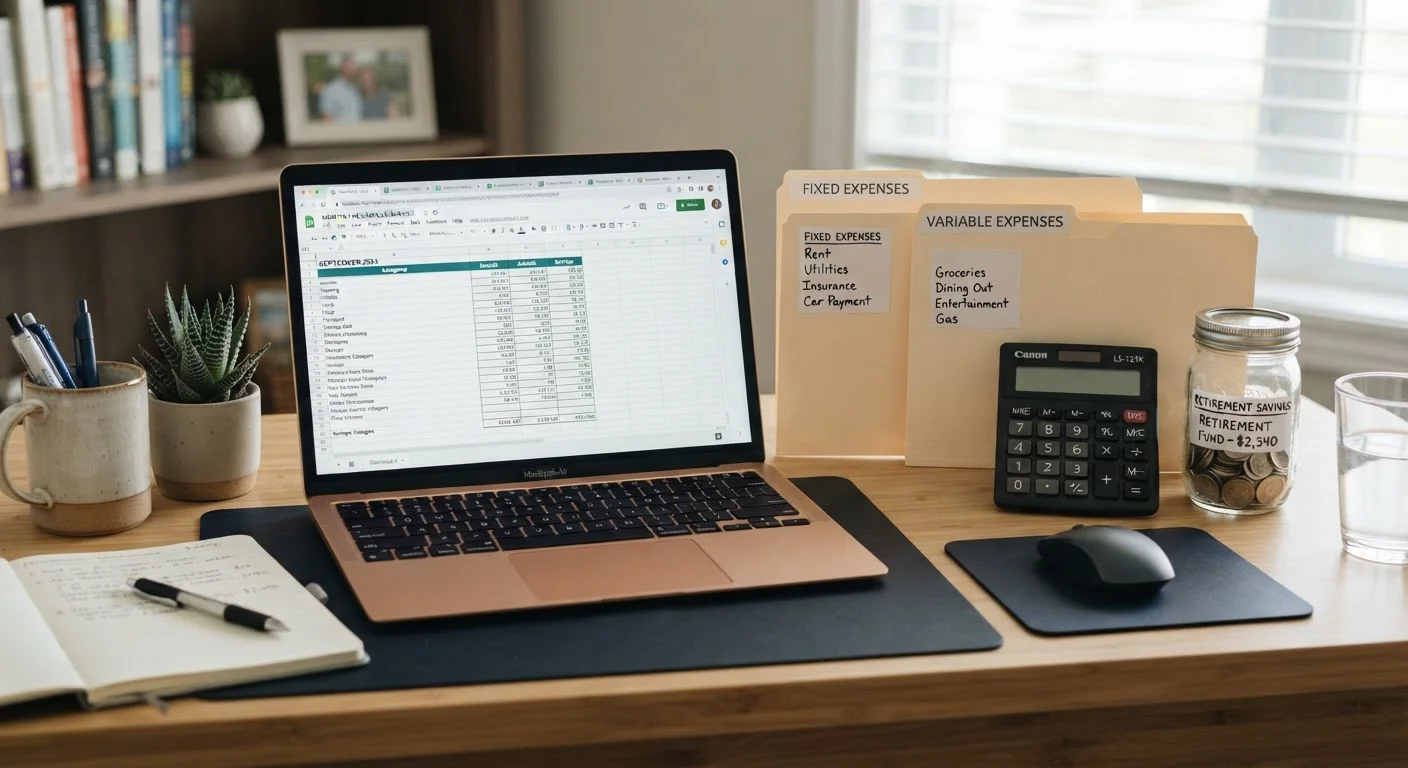
Photo: investorspaces.com editorial
—— In This Article
Key Takeaways
- Fixed expenses (rent, insurance, loan payments) are difficult to reduce quickly but can be renegotiated over time.
- Variable expenses (dining, subscriptions, entertainment) offer the most immediate room to redirect money toward retirement.
- Bureau of Labor Statistics data shows food away from home and entertainment account for a significant share of middle-aged household spending.
- Even small consistent redirections to a 401(k) or IRA compound meaningfully over a decade or more.
- Knowing your fixed expense floor tells you how much of your income is actually discretionary each month.
- A qualified financial adviser can help you assess which specific adjustments fit your household's situation.
What separates fixed from variable expenses
A fixed expense is any recurring cost that stays the same from month to month regardless of how you behave: your mortgage or rent payment, a car loan installment, a fixed-rate insurance premium. You committed to that number when you signed a contract, and it does not change whether you stay home all weekend or travel every week.
A variable expense changes based on choices you make: how often you eat out, how many streaming services you maintain, how much you spend on clothing or household goods. These costs appear on your bank statement every month, but the dollar amount moves depending on what you do.
The distinction matters because the two categories respond to different interventions. Cutting variable spending can happen this week. Reducing a fixed expense usually requires waiting for a renewal date, refinancing, or a larger lifestyle change such as moving to a less expensive home.
| Criterion | Fixed expenses | Variable expenses |
|---|---|---|
| Monthly predictability | Consistent, set by contract | Changes based on behavior |
| Speed of reduction | Slow (requires renegotiation or life change) | Fast (can start this week) |
| Examples | Mortgage, car loan, insurance premiums | Dining out, subscriptions, entertainment |
| Potential monthly savings | High if restructured | Moderate but immediate |
| Planning effort required | High (refinancing, downsizing, switching providers) | Low (habit changes, cancellations) |
| Best time to address | At contract renewal or life transition | Any month, starting now |
Why variable expenses are where savings hide
The Bureau of Labor Statistics Consumer Expenditure Survey consistently shows that households in the 45-to-54 age bracket spend notable sums on food away from home, entertainment, and personal care services. These are all variable costs. They are also the categories most people underestimate when they try to recall monthly spending from memory rather than reviewing actual account statements.
Consider a household spending $600 a month across dining out, takeout, and coffee purchases. Reducing that by a third and directing $200 to a 401(k) contribution does not require deprivation. It requires a deliberate decision followed by a habit adjustment. The IRS 2024 contribution limit for a 401(k) is $23,000 for workers under 50 and $30,500 for those 50 and older (including the $7,500 catch-up contribution). That $200 monthly redirection adds $2,400 a year toward either limit.
Subscriptions are another reliable source of unexamined variable spending. Many households carry overlapping streaming, software, and membership costs they no longer use regularly. A single afternoon reviewing bank statements often surfaces $50 to $150 in monthly charges that can be canceled and rerouted. For more on how these small decisions accumulate over time, see how everyday spending decisions affect your retirement timeline.
Fixed expenses: harder to cut, higher reward when you do
Fixed costs are not untouchable. They are just slower to change. A mortgage refinance, a housing downsize, or a switch to a lower-premium insurance plan can permanently reduce your monthly floor, freeing up dollars that stay available for retirement contributions indefinitely.
The challenge is that these moves require planning time, sometimes significant upfront cost, and often a change in lifestyle expectations. For middle-aged earners with children still at home or elderly parents to support, restructuring fixed costs can feel impossible in the short term.
The practical approach is to address variable expenses first for immediate wins, then schedule a review of each fixed cost at its next natural renewal point. Insurance policies, cell phone plans, and even car loans have regular renewal or refinance windows where switching costs are low. Mark those dates on your calendar and treat them as savings opportunities.
Redirecting spending toward retirement contributions does not require eliminating fixed costs overnight. It requires knowing what they are and planning around them.
$23,000
2024 IRS 401(k) contribution limit (under 50)
The IRS sets annual limits on pre-tax retirement contributions; workers 50 and older can contribute up to $30,500 including the catch-up amount.
$7,500
Catch-up contribution limit (age 50 and older)
Under IRS rules for 2024, workers aged 50 and above can add this amount on top of the standard 401(k) limit each year.
~13%
Share of spending on food for 45-to-54 age group
The Bureau of Labor Statistics Consumer Expenditure Survey shows food is one of the largest discretionary and semi-discretionary budget categories for middle-aged households.
Building a clearer picture of your spending floor
List every fixed expense you pay each month and add them up. That total is your committed floor: the minimum your household costs before any discretionary choice is made. Subtract it from your monthly take-home income. What remains is the pool from which you pay variable expenses and make retirement contributions.
Most people who do this exercise for the first time find their floor is higher than they assumed and their discretionary pool is smaller. That is useful information, not a reason for alarm. It tells you where to focus. If your fixed floor consumes 70% or more of take-home pay, variable cuts alone may not be enough and a longer-term fixed cost restructuring plan is worth building.
Budgeting methods differ in how they handle this split. Zero-based and envelope budgeting both treat fixed and variable costs differently, and understanding those differences can help you choose a framework that matches your household's structure.
Whatever approach you use, the goal is the same: give every dollar of discretionary spending a deliberate assignment before the month starts, so retirement contributions are not whatever is left over at the end.
This article is for informational purposes only and does not constitute personalized financial, tax, or investment advice. Contribution limits and tax rules are subject to change; consult IRS publications or a licensed financial adviser for guidance specific to your situation.
Budgeting & Saving Editorial Team
Budgeting & Saving Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile