
Zero-Based Budgeting vs. Envelope Budgeting for Retirement Savers
Compare two popular budgeting methods side by side to see which approach better supports consistent retirement saving at midlife.
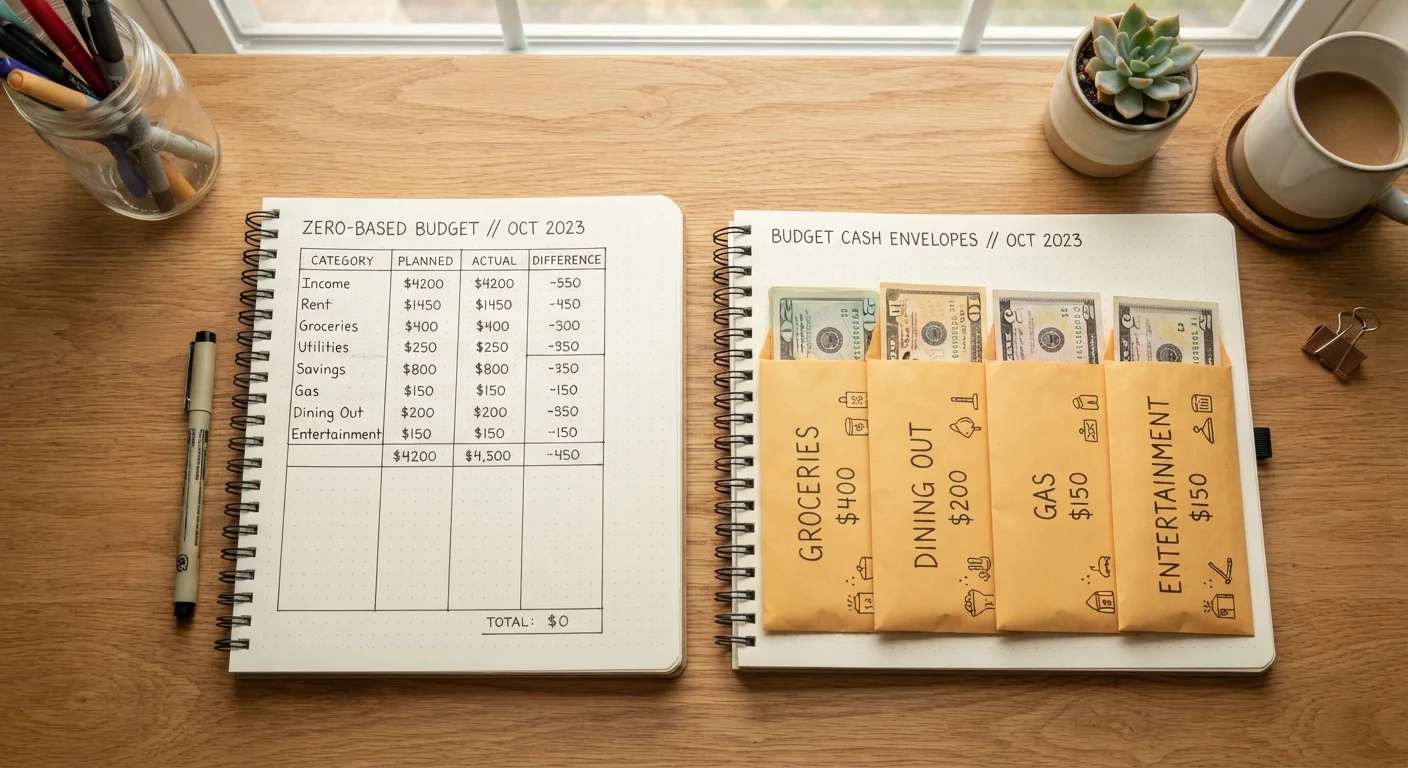
Photo: investorspaces.com editorial
—— In This Article
Key Takeaways
- Zero-based budgeting assigns every dollar a job each month, making retirement contributions an explicit, planned expense.
- Envelope budgeting uses preset spending caps per category, which can curb the variable overspending that erodes retirement savings.
- Both methods require active monthly setup; neither works on autopilot without regular review.
- Behavioral finance research supports that physical or visible limits reduce impulsive spending more than mental accounting alone.
- Middle-aged earners can adapt either method to maximize 401(k) or IRA contributions within IRS limits.
- Consulting a licensed financial planner helps you match a budgeting method to your full financial picture.
How each method works
Zero-based budgeting starts with your monthly take-home income and subtracts every planned expense until the balance reaches zero. Nothing is left unassigned. Retirement contributions, whether a 401(k) deferral or an IRA transfer, appear as a budget line just like the mortgage or utility bill. The method asks you to rebuild this allocation plan at the start of each month, which catches income changes and spending drift before they quietly reduce what you save.
Envelope budgeting divides spending into categories, each with a fixed cash amount for the month. When a category's envelope is empty, spending in that category stops. Retirement savings typically sit outside the envelope pool entirely: you move that money to a retirement account before filling any envelope, so it is never available to spend. Digitally, the same logic applies using sub-accounts or budget app buckets that show a hard remaining balance per category.
Both methods share one structural principle: retirement savings must be treated as a planned, first-priority allocation, not a residual. Common budgeting myths suggest you can simply spend less and save the difference, but that approach reliably fails when competing expenses expand to fill available income.
Where they differ for retirement savers
| Criterion | Zero-Based Budgeting | Envelope Budgeting |
|---|---|---|
| Monthly setup time | 30-60 min per month | Less once categories are set |
| Handles variable income | Well: rebuild each month | Poorly: static amounts can misalign |
| Retirement contribution visibility | Explicit budget line | Moved out before envelopes are filled |
| Overspending prevention | Relies on reviewing plan | Hard stop when envelope is empty |
| Requires tracking tool | Yes: spreadsheet or app | Optional: works with cash or app |
| Best for | Detail-oriented planners | Tactile or visual learners |
The practical gap between these methods shows up in two places: monthly effort and spending flexibility. Zero-based budgeting takes 30 to 60 minutes at the start of each month to assign every dollar. If your income varies, that rebuilding step is genuinely useful because you are adjusting contribution amounts to reflect what you actually earned. Envelope budgeting requires less monthly recalculation once your category amounts are set, but it is less flexible when a large unexpected expense arrives.
For middle-aged earners trying to maximize retirement contributions, the IRS sets annual contribution limits for workplace plans and IRAs. Zero-based budgeting makes it straightforward to calculate exactly how much per paycheck must be deferred to hit those annual limits, because you control every line in the budget. Envelope budgeting's strength is different: it prevents the category-level overspending (dining out, subscriptions, clothing) that quietly diverts money that could have gone to savings. Variable expenses are where retirement savings most often hide, and envelope budgeting puts a hard cap on exactly that spending.
Behavioral factors that affect which method sticks
Research in behavioral finance, including work associated with the concept of mental accounting, suggests that people manage money more carefully when funds are visibly separated into specific purposes rather than pooled. Envelope budgeting operationalizes that directly. When a dining envelope holds $300 and the cash is physically countable, the decision to spend $80 on dinner is more deliberate than swiping a card against a mental budget category.
Zero-based budgeting produces similar intentionality through documentation rather than physical separation. Writing down that you plan to save $500 this month and spend $200 on groceries creates a commitment that is stronger than general intent, but it depends on the person actually reviewing that plan when making spending choices. People who find the monthly rebuilding process engaging tend to stick with zero-based budgeting. People who find it tedious often abandon it within three months.
If you have tried zero-based budgeting before and stopped, consider whether the monthly rebuild felt like maintenance or a chore. If the latter, envelope budgeting's simpler structure may produce better long-run consistency, which matters more than methodological purity. A monthly budget review supports either method by flagging when allocations drift from your retirement targets.
Which method fits your retirement timeline
At midlife, the math on retirement saving is less forgiving than it was at 30. Compound growth has less time to work, so the actual dollar amount directed to retirement each month carries more weight. Both methods can support meaningful contributions, but they suit different financial profiles.
Zero-based budgeting gives you a clear monthly calculation: income minus all expenses, with retirement savings as a named line before discretionary spending. If you have a mortgage, college costs, and aging-parent expenses competing for the same paycheck, the line-item format forces honest trade-off decisions rather than vague optimization. The 50/30/20 framework can supplement zero-based budgeting by providing percentage targets for needs, wants, and savings within your zero-based structure.
Envelope budgeting fits earners whose income is predictable but whose spending habits are the problem. If you know roughly what you earn each month but still find retirement contributions getting crowded out, capping each spending category prevents that erosion structurally rather than relying on willpower. The trade-off between emergency fund building and retirement contributions is a related allocation decision both methods require you to address explicitly.
This article is for informational purposes only and does not constitute personalized financial, tax, or investment advice. Consult a qualified financial adviser before making decisions about your retirement savings strategy.
Budgeting & Saving Editorial Team
Budgeting & Saving Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile